Back to blog

Micron's share price has been consolidating since the beginning of the year: Is this an opportunity to buy bargains?

Micron Technology, the American chip giant, presented its financial results for the second quarter of fiscal 2025, which clearly exceeded analysts' expectations, while confirming the company's growing importance in the field of AI and data centers. Despite the risks the company has pointed out, it is possible that the stock has the potential to break free from consolidation based on key fundamentals. Will they succeed?

Micron's share price has been consolidating since the beginning of the year: Is this an opportunity to buy bargains?

What is the outlook for the next quarter?

Micron presented reasonably optimistic expectations for the coming period, with management estimating revenue at $8.8 billion, which is higher than the market's estimate of $8.55 billion. Following this, earnings per share should reach $1.57, again above expectations at $1.48. [1] 

However, despite strong growth, gross margin is expected to decline slightly to 36.5%, suggesting a possible increase in production costs or stronger price competition from other players in the segment. However, this prediction does not reflect the overall context of the company's financial condition, nor does it diminish the positive, bullish sentiment around the company as demand for their specialized AI chips and high-performance memory continues to grow.

Demand for AI chips and strengthening the data center segment

If you're wondering about Micron's most influential growth factor, the answer won't surprise you. Traditionally, the expansion is driven by the demand for the aforementioned AI chips, which was subsequently reflected in revenues from data centers, which increased up to three times Overall, sales in the monitored quarter increased by 38% year-on-year. In AI, high-bandwidth memory (HBM) was a key success factor, contributing $1 billion to total revenue in the second quarter alone. This segment is extremely important for the company, as tech giants such as Nvidia, AMD and Intel continue to invest heavily in the development of AI chips and other computing solutions that require high-performance memory modules.

Stock development and market attitude

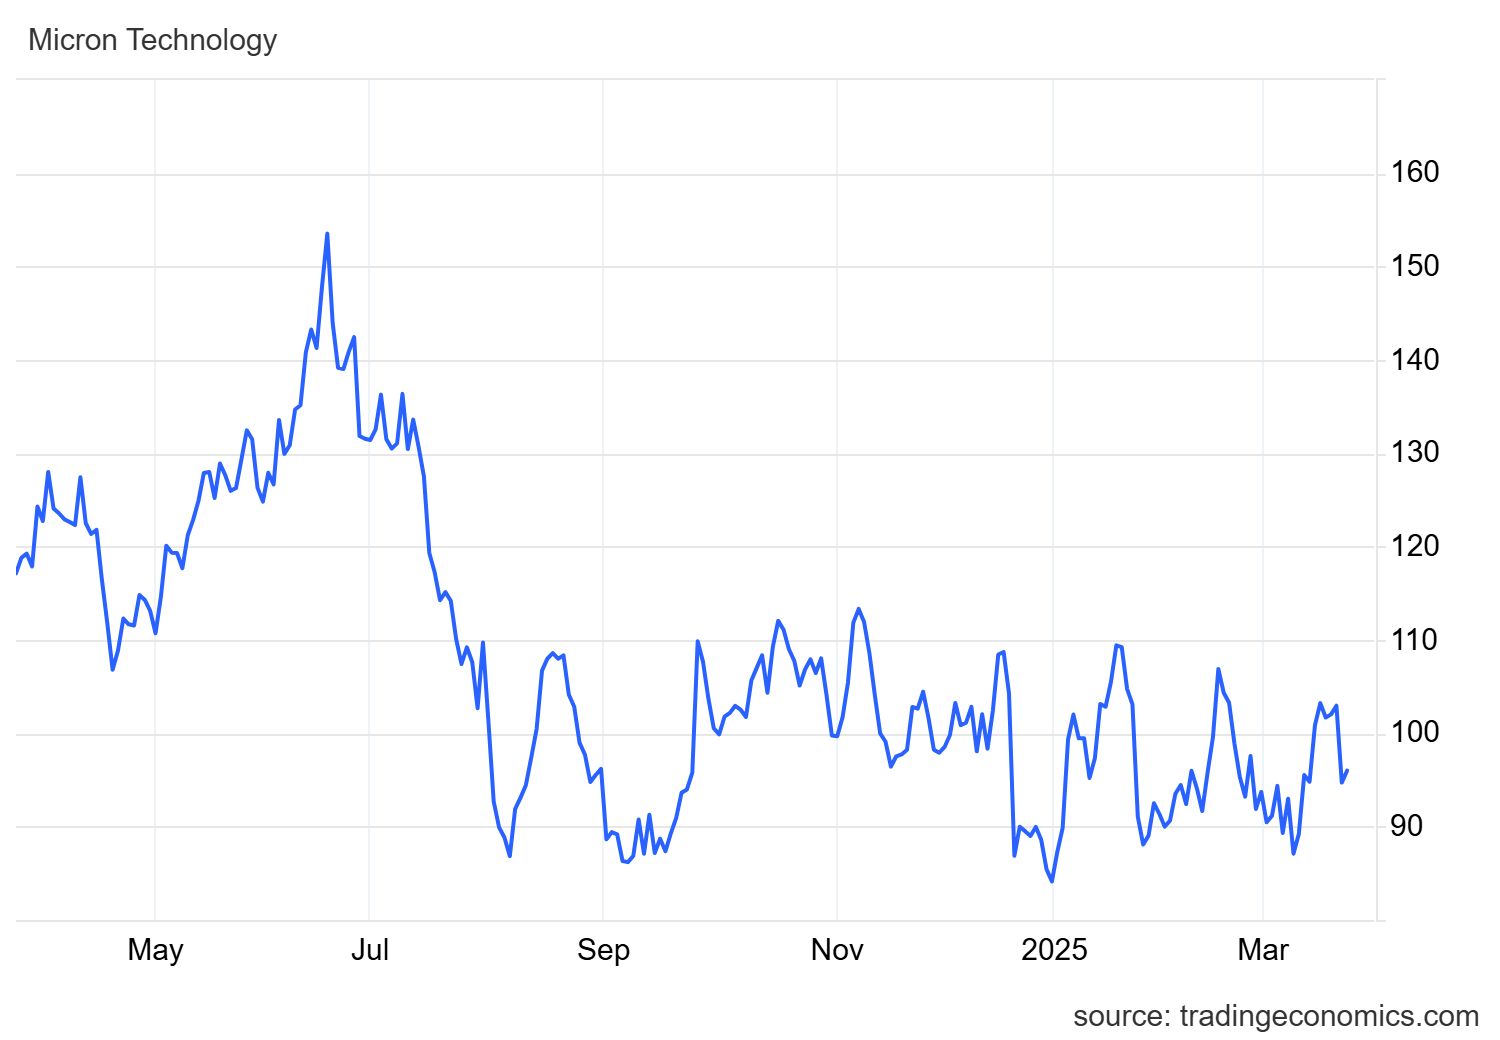
Looking at the share price of this giant, the situation is a little less clear. Since the beginning of the year, the price development could be characterized primarily as corrective, which is a natural part of the capital market. There are periods when price activity falls, but at the same time it is an opportunity for investors who are not yet interested. If a fundamentally strong company, which Micron is, declines in the short term, there is also an opportunity to buy at a better price compared to entering near the peak of performance. *
mu_us

Source: Tradingeconomics*

In addition, the company's CEO Sanjay Mehrotra said in the official earnings report that Micron is on track for record revenue and a significant improvement in profitability, which can be another positive signal. [2]

Final assessment and long-term outlook

Micron Technology showed significant growth in the second quarter, currently benefiting primarily from the soaring demand for AI chips and data centers. This trend is likely to continue in the coming quarters as leading technology companies continue to expand AI capabilities and cloud solutions. At the same time, the company is in a position to benefit from this development as much as possible, thanks to a strong product portfolio. While the expected slight reduction in gross margin in the third quarter may signal some near-term challenges, Micron still shows a steady growth trajectory with the possibility of further improvement for the rest of the fiscal year.

* Historical figures are not a guarantee of future returns.

[1] , [2] Forward-looking statements represent assumptions and current expectations that may not be accurate or are based on the current economic environment, which is subject to change. These statements do not guarantee future performance. Forward-looking statements involve risk and uncertainty by their nature because they relate to future events and circumstances that cannot be foreseen, and actual developments and results may differ materially from those expressed or implied in any forward-looking statements.   

Warning! This marketing material is not and should not be construed as investment advice. Data relating to the past are not a guarantee of future returns. Investing in foreign currency can affect returns due to fluctuations. All securities trades can lead to both profits and losses. Forward-looking statements represent assumptions and current expectations that may not be accurate or are based on the current economic environment, which is subject to change. These statements do not guarantee future performance. InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., regulated by the National Bank of Slovakia.

Resources:

https://finance.yahoo.com/news/micron-gives-upbeat-sales-forecast-202305902.html

https://www.cnbc.com/2025/03/20/micron-mu-q2-earnings-2025.html

https://investors.micron.com/static-files/df96216e-3e07-4b97-a4ef-df0a5fa684d6

https://investors.micron.com/news-releases/news-release-details/micron-technology-inc-reports-results-second-quarter-fiscal-2025

InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., with its registered office at Slávičie údolie 106, Bratislava – Staré Mesto district, 811 02. The company is registered in the Commercial Register of the Municipal Court Bratislava III, Section: Sa, File No.: 4295/B, ID No.: 36 853 054, VAT No.: 2022505419.

CAPITAL MARKETS, o.c.p., a.s. is a securities dealer pursuant to Section 55(1) of Act No. 566/2001 Coll. on Securities and Investment Services and on Amendments to Certain Acts, as amended (hereinafter the “Securities Act”). On October 30, 2007, CAPITAL MARKETS, o.c.p., a.s. was granted, by Decision No. OPK-2297/2007 of the National Bank of Slovakia -PLP, a license to provide investment services pursuant to Section 54(2) in conjunction with Sections 59(2) and (3) of the Securities Act, which was extended in accordance with the provisions of the Securities Act by Decision No. OPK-1830/2008-PLP dated April 21, 2008, Decision No. OPK-11601-1/2008 dated January 28, 2009, Decision No. ODT-5059-3/2012 dated July 23, 2012, and Decision No. ODT-9332/2014-1 dated October 21, 2014.

Read more

Lamb Weston Surprises the Stock Market: Profit Falls 55%, Shares Jump 7.5%

Lamb Weston Surprises the Stock Market: Profit Falls 55%, Shares Jump 7.5%

Frozen french fry manufacturer Lamb Weston announced its results on October 6, 2026, revealing a striking discrepancy between reported profits and the stock market’s reaction. Net income plummeted 55% year-over-year, yet investors responded by buying shares. The company exceeded expectations and raised its full-year outlook. Sales growth in North America and cost-cutting measures suggest that changes in the company’s operations are beginning to pay off. The question remains, however, whether this progress will be enough to resolve problems overseas. [1]

TD SYNNEX Far Exceeded Expectations: Revenue Jumped 38%, but Shares Fell After the Earnings Report

TD SYNNEX Far Exceeded Expectations: Revenue Jumped 38%, but Shares Fell After the Earnings Report

TD SYNNEX reported results that, at first glance, look very strong and confirm that the company is benefiting from growing demand for technology infrastructure. Upon closer inspection, however, the picture is not entirely clear-cut. Behind the record numbers lies a combination of rapid expansion, shifting margins, and significant cash flow fluctuations, which investors have begun to view with far greater sensitivity than revenue growth alone. It is precisely the difference between what the income statement shows and what is happening beneath the surface that makes TD SYNNEX’s latest quarter a much more interesting story than the headline numbers alone would suggest.

AutoZone Surprises Wall Street with Earnings: EPS Jumps 15%, but Weaker Sales Reveal Pressure on Customers

AutoZone Surprises Wall Street with Earnings: EPS Jumps 15%, but Weaker Sales Reveal Pressure on Customers

AutoZone closed fiscal year 2026 with results that appear very strong at first glance. Fourth-quarter revenue rose 5.6% year-over-year to $6.59 billion, net income increased to $931.6 million, and earnings per share reached $56.05, approximately 15% higher than a year ago and above Wall Street expectations. Beneath the surface, however, a weakness remains. Comparable sales growth fell short of forecasts, and American DIY car repairers continue to curb their purchases.1

Oracle Gains Momentum in AI: Cloud Revenue Grows 121%, Contracted Order Volume Reaches $664 Billion

Oracle Gains Momentum in AI: Cloud Revenue Grows 121%, Contracted Order Volume Reaches $664 Billion

Oracle kicked off the new fiscal year with results that once again confirmed that its transformation toward the cloud and artificial intelligence is gaining momentum. The company exceeded market expectations and demonstrated significant acceleration in the areas where it has directed the bulk of its investments in recent years. Behind the strong numbers, however, lies a question that will become increasingly important for investors. Oracle is growing rapidly, but the path to further expansion will be extremely costly. [1]