English

 Slovak
 Czech
 Hungarian
 Italian
 Polish
 Slovenian


The company’s consolidated revenue reached $5.59 billion, compared to $3.65 billion a year ago, representing growth of more than 50%. However, this comparison is significantly influenced by Foot Locker, which was not yet part of the group in the same quarter last year. The earnings picture was much weaker. Net income fell from $381 million to $315 million, and earnings per share decreased from $4.71 to $3.50. On an adjusted basis, earnings per share fell from $4.38 to $3.53. Meanwhile, the adjusted operating margin plummeted from 13.0% to 8.1%, indicating that the group’s growth in size has not yet led to a corresponding increase in profitability.[1]
The good news is that DICK’S original business remains in very good shape. Its revenue reached approximately $3.85 billion, and comparable sales rose by 4.9%, with both the number of transactions and the average purchase value increasing. The company also benefited from strong demand linked to the World Cup. Segment profit for DICK’S’s core business reached $485 million, compared to $475 million a year ago. The results thus show that the company’s core business continues to perform very well. The problem lies almost entirely on the other side of the group.1
Foot Locker has become the main problem
Foot Locker posted quarterly revenue of approximately $1.74 billion, but comparable sales fell by 3.6%, and the segment ended the quarter with an operating loss of nearly $32 million. Management attributes the weak numbers to challenging conditions in the athletic footwear market. Foot Locker is more heavily reliant on traditional sneaker models, retro products, and the success of major product launches. There were fewer of these during the quarter, and according to CEO Ed Stack, they also performed worse than both the company and the industry itself had expected. Rising inventory levels subsequently forced both brands and retailers to cut prices more aggressively.1[2]
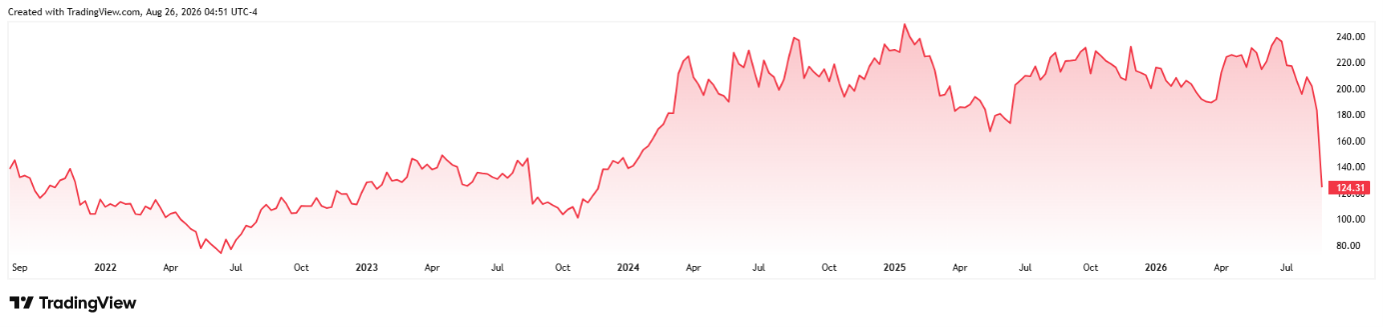
Dick’s Sporting Goods Stock Price Performance Over the Past Five Years*
This is an unfortunate turn of events for an acquisition in which management had high expectations. DICK’S completed the purchase of Foot Locker in September 2025 for a total consideration of approximately $2.5 billion. At the time, the company expected cost synergies of $100 million to $125 million and a positive impact of the transaction on earnings per share as early as fiscal year 2026. As recently as May, management projected that Foot Locker would generate segment earnings of $110 million to $150 million this year. Following the latest results, it now expects a loss of $40 million to $80 million. The difference between the midpoints of these two ranges amounts to approximately $190 million in just three months.1 [1]
The sneaker market is undergoing a painful transformation
At the same time, Foot Locker’s problems are not solely the result of poor integration. Consumer demand in the athletic footwear market is shifting. According to management, traditional and lifestyle models no longer appeal to customers as they did in the past, while new products focused on performance, health, and wellness are achieving better results. With higher household spending on groceries and energy, American consumers are also being more cautious about non-essential purchases. For Foot Locker, this combination is particularly unfavorable, as its business model is heavily reliant on major brands, new product launches, and shopping center foot traffic.12
DICK’S results therefore also impacted other companies in the industry. Nike’s stock fell by approximately 3.3% following the announcement. Earlier, British retailer JD Sports had also lowered its earnings outlook after weaker sales in North America. Investors thus did not view DICK’S results as merely an isolated problem for a single company. Foot Locker’s weakness raised a broader question: after years of strong interest in sneakers, is consumer behavior beginning to shift, and do some major sports brands have too much inventory on the market for products that customers no longer desire as intensely.12
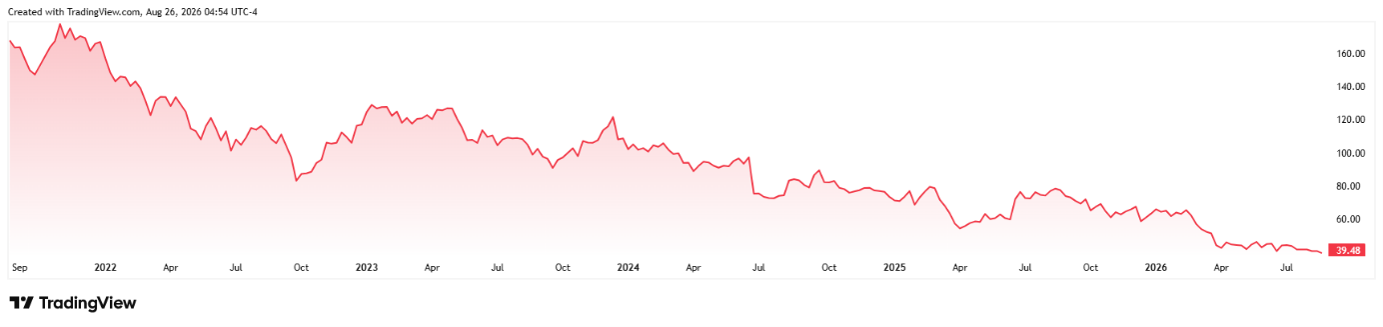
Nike’s stock price performance over the past five years*
The outlook has deteriorated dramatically over the past three months
The biggest disappointment for investors was not the quarter itself, but what the company expects for the rest of the year. DICK’S lowered its full-year revenue forecast to $21.9 billion to $22.2 billion from the previous range of $22.1 billion to $22.4 billion. The earnings outlook deteriorated even more significantly. Adjusted earnings per share are now expected to reach only $11 to $12, whereas as recently as May, the company had forecast $13.50 to $14.50. The midpoint of the new range is thus approximately 18% lower than the previous estimate. It is precisely this sharp shift in expectations that explains why the market reacted much more harshly than it typically does when quarterly forecasts are missed.2 [2]
The difference between the two companies is also evident in their full-year outlook. DICK’S continues to expect comparable sales growth of 2.5 to 4.0% for its core business, while Foot Locker now anticipates a decline of 2% or stagnation. DICK’S segment profit is expected to reach $1.54 to $1.60 billion, while Foot Locker is projected to post a loss of $40 to $80 million. In addition, the company is continuing an extensive restructuring of its acquired business. Costs associated with inventory optimization, the closure of underperforming stores, and other changes have already reached approximately $516 million and could total as much as $750 million.1 [3]
The success of the entire acquisition is now at stake
DICK’S acquired Foot Locker to transform the American sporting goods retailer into a global player with a much stronger position in the sneaker market and better relationships with the world’s leading brands. The group currently operates 3,104 stores, with the Foot Locker business alone accounting for 2,478 locations, including licensed stores. However, DICK’S closed 110 Foot Locker and affiliated brand stores during the first half of the year, with dozens of them identified as unproductive assets. Management must therefore simultaneously modernize stores, adjust the product mix, reduce inventory, and restore growth without allowing additional costs to further squeeze the group’s profitability.1
DICK’S financial position remains manageable, but the margin for error has narrowed. At the end of the quarter, the company had $914 million in cash; long-term debt and finance lease obligations totaled approximately $1.91 billion; and inventory rose to $5.57 billion. The company is also continuing to invest, with planned gross capital expenditures of approximately $1.6 billion for the full year. For investors, therefore, one question will be decisive in the coming quarters. Not whether the original DICK’S business can grow, which it has so far confirmed its strength, but whether management can turn around Foot Locker’s performance before weaker profitability and high transformation costs begin to permanently erode the value of the entire group. The answer to this question will determine whether the historic stock plunge was an overreaction by the market or the first serious warning of a problem that may plague the company for several more years.1 [4]
[1,2,3,4] Forward-looking statements are based on assumptions and current expectations, which may be inaccurate, or on the current economic environment, which is subject to change. Such statements are not guarantees of future performance. They involve risks and other uncertainties that are difficult to predict. Actual results may differ materially from those expressed or implied in any forward-looking statements.
* Past performance is no guarantee of future returns.
[1] https://s27.q4cdn.com/812551136/files/doc_financials/2026/Q2/2Q26_DKS_Press-Release.pdf
[2] https://www.reuters.com/business/dicks-sporting-goods-cuts-annual-forecasts-athleticwear-demand-weakens-2026-08-25/