
 English

 Slovak
 Czech
 Hungarian
 Italian
 Polish
 Slovenian


What exactly did Salesforce report?
In Q1 FY27, Salesforce generated revenue of $11.1 billion, representing year-over-year growth of 13% and 12% on a constant-currency basis. Of this, $10.6 billion came from subscription and support revenue, with growth of 14% in reported currency and 12% on a constant-currency basis. The remainder came from professional services and other services, which grew more slowly and represent a smaller portion of the overall mix. These revenues also include the contribution from the newly acquired Informatica, which brought in $444 million and increased year-over-year revenue growth by approximately 5 percentage points.[1]
In terms of profitability, the company reported GAAP EPS of $2.42, representing year-over-year growth of 52%. Non-GAAP EPS reached $3.88, a 50% increase compared to the same period last year. The GAAP operating margin reached 21.1%, while the non-GAAP operating margin was 34.8%, significantly above the company’s long-term target of approximately 30%. This combination of rapid growth and high margins is one of the main reasons why Salesforce remains an attractive name for investors even in a higher-rate environment.1
Orders, RPO, and Demand Signals
The key metric the market looks at for software companies is not just quarterly revenue itself, but also future orders. Salesforce reports a total remaining performance obligation (RPO) of $67.9 billion, representing year-over-year growth of 11%. Current RPO, i.e., obligations for the next 12 months, reached $33.6 billion and grew by 14% on a constant-currency basis. These figures suggest that demand for Salesforce’s services is growing, though the pace of RPO growth is slightly lower than the pace of revenue growth when accounting for the Informatica effect.1
The market, however, looks not only at absolute numbers but also at how they compare to expectations. According to data compiled by several analytical platforms, the market expected total RPO to be closer to $68.9 billion. The actual figure of $67.9 billion is therefore not a weak number, but it is a slight miss compared to the consensus, signaling that growth in new orders is not as aggressive as the market had hoped. It is precisely this detail that became one of the main reasons why the market reaction did not reflect the strength of the overall results.[2]
AI, Agentforce, and Monetizing Growth
Salesforce is increasingly basing its growth thesis on AI and what the company calls AI CRM. In the report and comments on the results, management emphasizes that annual recurring revenue (ARR) from Agentforce and Data 360 products reached approximately $3.4 billion. Of this, Agentforce alone accounts for around $1.2 billion in ARR, according to the earnings commentary, while Data 360 accounts for approximately $2.2 billion, with a significant portion coming from cloud services acquired with Informatica.1
The number of customers with Agentforce in production grew by approximately 50% during the quarter, and more than half of new AI orders are based on a consumption-based or credit-based model, which allows for incremental revenue growth as usage increases. This is an important signal for investors, as it shows that Salesforce is not limiting its AI monetization to fixed licenses but is striving to build a model that grows alongside AI adoption at the customer level.1
FY27 Outlook and Market Reaction
The most sensitive part of the results was the full-year outlook. Salesforce raised its revenue estimate for fiscal year 2027 to a range of $45.9 billion to $46.2 billion, representing approximately 11% growth at the midpoint. However, according to data, the market had expected a figure closer to $46.1 billion to $46.2 billion, so the upward revision was viewed more as a technical adjustment than a strong growth signal.[3] [1]
The company expects a non-GAAP operating margin of 33% to 34% and free cash flow in a range implying an FCF margin of around 30% to 31%. This is a very healthy profitability profile, but for growth-oriented investors, it is more important whether revenue can sustain double-digit growth over the long term. The decline in the stock price following the earnings release, despite strong EPS, indicates that the market currently views Salesforce primarily through the lens of future growth, not past results.1 [2]
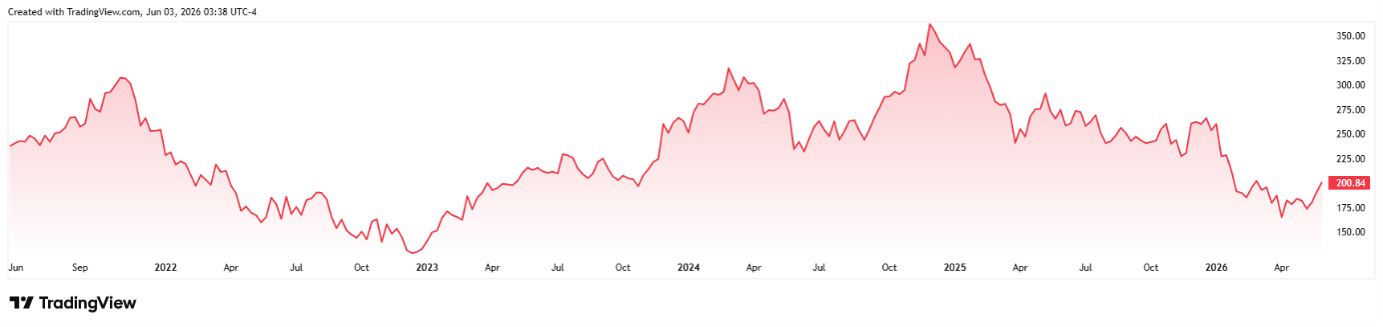
Salesforce stock price performance over the past five years*
What's a Positive Sign and What's a Cause for Concern for Investors
For investors following Salesforce, there are three key signals from these results. The first is that the company continues to grow revenue at a double-digit pace while maintaining a non-GAAP operating margin of around 35% and an FCF margin of around 30%. This is a combination that remains very strong even compared to other major software names. The second is that RPO and cRPO are growing, but they are running up against market expectations, and even a small miss relative to consensus is reflected in stock volatility. The third is that AI is no longer just a marketing buzzword, but it is not yet the main driver of revenue either, so the valuation will depend on how quickly this AI contribution translates into ARR.
On the other hand, some of the short-term fluctuations in the stock price, which arise mainly from the difference between the company’s guidance and the consensus in terms of tenths of a percentage point of growth, may be cause for concern.* For longer-term investors, the RPO trajectory, the pace of Agentforce adoption, and the company’s actual ability to maintain high margins amid growing investments in AI infrastructure carry greater weight. If Salesforce can demonstrate in the coming quarters that AI ARR is growing significantly faster than the rest of the business while total RPO growth stabilizes around the low double digits, today’s cautious sentiment may in hindsight appear more as an opportunity than a problem.
[1,2] Forward-looking statements are based on assumptions and current expectations that may be inaccurate, or on the current economic environment, which may change. Such statements do not constitute a guarantee of future performance. They involve risks and other uncertainties that are difficult to predict. Results may differ materially from those expressed or implied in any forward-looking statements.
* Past performance is no guarantee of future returns.
Warning! This marketing material is not and should not be construed as investment advice. Past performance is no guarantee of future returns. Investing in foreign currencies may affect returns due to fluctuations. All securities transactions may result in both gains and losses. Forward-looking statements represent assumptions and current expectations that may not be accurate or are based on the current economic environment, which may change. These statements do not guarantee future performance. InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., regulated by the National Bank of Slovakia.
InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., with its registered office at Slávičie údolie 106, Bratislava – Staré Mesto district 811 02. The company is registered in the Commercial Register of the Municipal Court Bratislava III, Section: Sa, File No.: 4295/B, ID No.: 36 853 054, VAT No.: 2022505419.
CAPITAL MARKETS, o.c.p., a.s. is a securities dealer pursuant to Section 55(1) of Act No. 566/2001 Coll. on Securities and Investment Services and on Amendments to Certain Acts, as amended (hereinafter the “Securities Act”). On October 30, 2007, CAPITAL MARKETS, o.c.p., a.s. was granted, by Decision No. OPK-2297/2007 of the National Bank of Slovakia-PLP, a license to provide investment services pursuant to Section 54(2) in conjunction with Sections 59(2) and (3) of the Securities Act, which was extended in accordance with the provisions of the Securities Act by Decision No. OPK-1830/2008-PLP dated April 21, 2008, Decision No. OPK-11601-1/2008 dated January 28, 2009, Decision No. ODT-5059-3/2012 dated July 23, 2012, and Decision No. ODT-9332/2014-1 dated October 21, 2014.
[1] https://investor.salesforce.com/news/news-details/2026/Salesforce-Delivers-Record-First-Quarter-Fiscal-2027-Results/default.aspx
[2] https://sg.finance.yahoo.com/news/salesforce-crm-q1-earnings-taking-213002457.html
[3] https://www.cnbc.com/2026/05/27/salesforce-crm-q1-earnings-report-2027.html



