English

 Slovak
 Czech
 Hungarian
 Italian
 Polish
 Slovenian


Amazon closed 2025 with truly impressive figures. Total revenues of USD 213.39 billion exceeded market expectations, representing clear evidence of the strength of its ecosystem. Net profit increased year-on-year to USD 21.19 billion, reflecting growing efficiency in business operations. Despite a slight shortfall in earnings per share (EPS), where the company delivered USD 1.95 compared to the estimated USD 1.97, the company’s operational engines are in the best condition they have been in for years.
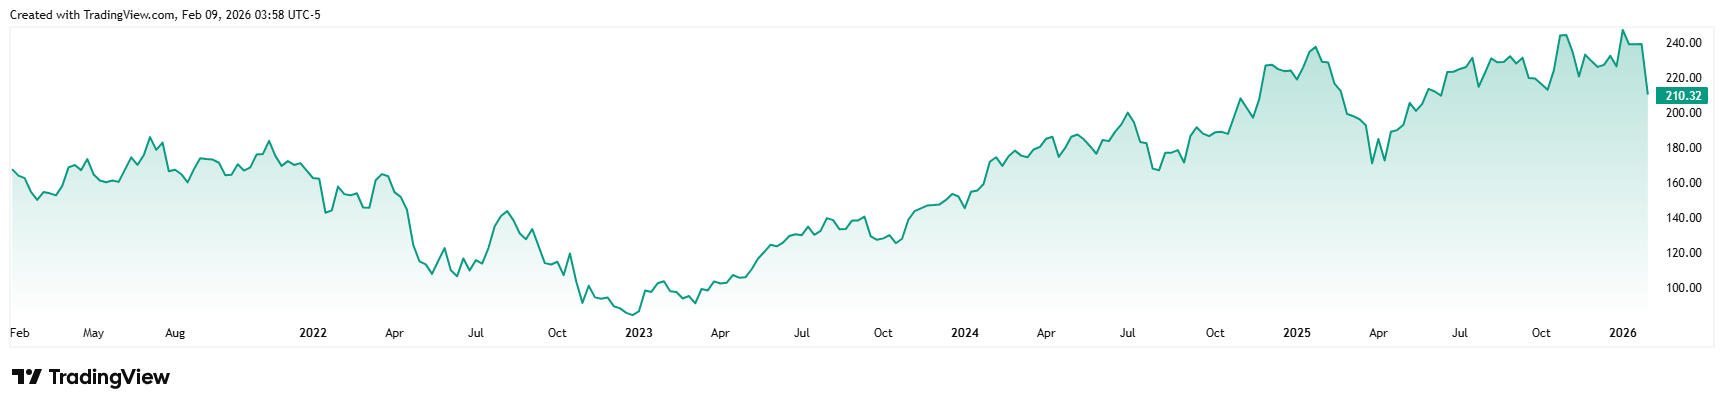
Amazon share price performance over the past five years
Synergy of Cloud and Advertising
The key to understanding Amazon’s current market value no longer lies exclusively in consumer goods sales, but in the combination of its technological divisions, which demonstrate exceptional stability and growth potential. A dominant role in this process is played by the cloud division Amazon Web Services (AWS), which generated revenues of USD 35.58 billion during the observed period. With a year-on-year growth rate of 24%, this represents the strongest acceleration over the past 13 quarters, as confirmed by CEO Andy Jassy’s statements about almost unlimited demand for artificial intelligence infrastructure.
In parallel with the technological pillar, the digital advertising segment is also developing dynamically. With revenues exceeding USD 21 billion and a year-on-year increase of 23%, it has definitively strengthened Amazon’s position as the third-largest global player in this industry, immediately behind giants Alphabet and Meta. For both investors and the company itself, it is crucial that this segment is becoming an important generator of high-margin revenues that help finance further expansion.
Decline in Share Price – Why?
The most discussed part of the report became the outlook for 2026. Amazon announced plans to invest an astronomical USD 200 billion through capital expenditures. For comparison, analysts had expected a figure USD 50 billion lower. These funds will primarily be directed toward building data centers, developing proprietary AI chips, robotics, and a low Earth orbit satellite network. The market reacted to this extensive investment burden with a decline in the share price of approximately 8%. Investors are ultimately concerned about whether these funds will translate into profits quickly enough.[1]
Efficiency and Restructuring
A paradox amid such massive investments is the ongoing effort to streamline the corporate structure. Last week, Amazon announced the layoff of an additional 16,000 employees, following the October wave of workforce reductions. The goal is to reduce bureaucracy and free up resources for technological priorities. Although Amazon employs 1.57 million people globally, the vast majority are logistics workers, while the layoffs strategically target administrative roles.
Market Context
It is probably no surprise that Amazon is not alone in this investment arms race. Companies such as Alphabet and Meta have also announced radical increases in spending on AI infrastructure. In the cloud battle, however, Amazon faces fierce competition — while AWS grew by 24%, Microsoft Azure reported growth of 39% and Google Cloud as much as 48%.
For Investors
The current decline in Amazon’s share price can be interpreted as a manifestation of short-term market nervousness regarding unprecedented capital expenditures. What is essential is that the company’s fundamentals remain exceptionally strong. Successful monetization of cloud services and advertising, combined with the 2026 investment plan, suggests that management has identified artificial intelligence as an existential opportunity. In conclusion, it can be said that if Amazon is able to efficiently capitalize on these investments, the current market correction may, in the medium term, appear as a strategically attractive entry point for building a long-term position. [2]
* Data relating to the past are not a guarantee of future returns.
[1,2] Forward-looking statements represent assumptions and current expectations that may not be accurate or may be based on the current economic environment, which may change. These statements do not guarantee future performance. Forward-looking statements inherently involve risks and uncertainties, as they relate to future events and circumstances that cannot be predicted, and actual developments and results may differ materially from those expressed or implied in any forward-looking statements.
Disclaimer! This marketing material is not and must not be understood as investment advice. Data relating to the past are not a guarantee of future returns. Investing in foreign currencies may affect returns due to fluctuations. All securities transactions may result in both profits and losses. Forward-looking statements represent assumptions and current expectations that may not be accurate or based on the current economic environment, which may change. These statements do not guarantee future performance. InvestingFox is a trading brand of CAPITAL MARKETS, o.c.p., a.s., regulated by the National Bank of Slovakia.
Sources:
https://www.cnbc.com/2026/02/05/amazon-amzn-q4-earnings-report-2025.html