
 English

 Slovak
 Czech
 Hungarian
 Italian
 Polish
 Slovenian


What was actually agreed upon
Under the announced structure, Unilever and its shareholders will receive a stake representing 65% of the fully diluted equity of the new combined company, with Unilever itself retaining a 9.9% stake and receiving a one-time cash payment of $15.7 billion. The transaction values Unilever Foods at approximately $44.8 billion and is structured as a Reverse Morris Trust, a tax-efficient arrangement designed to reduce tax costs for Unilever and its shareholders. From a market perspective, this is a large and unusually structured deal, as it is not a straightforward sale of a single division for cash, but a combination of cash and an equity stake in the new entity. This means that Unilever is not completely divesting its food business but is retaining significant exposure to the future development of the new group.1
Why Unilever is spinning off its food business
This move fits into a broader strategy in which Unilever is increasingly focusing on faster-growing areas such as beauty, personal care, and home care, while the food division has been a stable but slower-growing segment in recent years. Although the food business accounts for more than a quarter of the group’s revenue and contributes to overall margins, its growth has lagged behind other parts of the company as well as Unilever’s own medium-term targets. This is the essence of the entire transaction. Unilever is not selling a weak or loss-making business, but a segment that is profitable, yet no longer fits the vision of what a company with a higher growth profile and a more attractive stock market valuation should look like.[2]
Why this is a transformative deal for McCormick
For McCormick, this is a significantly bigger story than for Unilever, as the company is dramatically expanding its global presence in spices, sauces, seasonings, cooking aids, and more through this deal, and is combining its own brands with icons like Knorr and Hellmann’s. According to the official announcement, the combined company aims to drive higher growth in attractive categories, leverage greater geographic reach, and better integrate retail with the foodservice channel.
McCormick’s management also states that the new company should aim for revenue growth in the range of 3 to 5% by the third year and annual cost synergies of $600 million net of reinvestments. This is important because without such synergies, the market would view this deal more as a significant expansion of scale than as a true driver of growth and profitability.1
Why investors reacted negatively
Although at first glance this may seem like a strategically logical merger, investors immediately focused on the risks. Following the announcement, Unilever shares fell by approximately 7% and McCormick shares by about 5%, as the market grappled with the deal’s complex structure, the lengthy time to closing, integration challenges, and potential regulatory scrutiny. Investors don’t just want to hear that a larger company will be created; they also want to see a clear and rapid path to higher shareholder value.[3] *
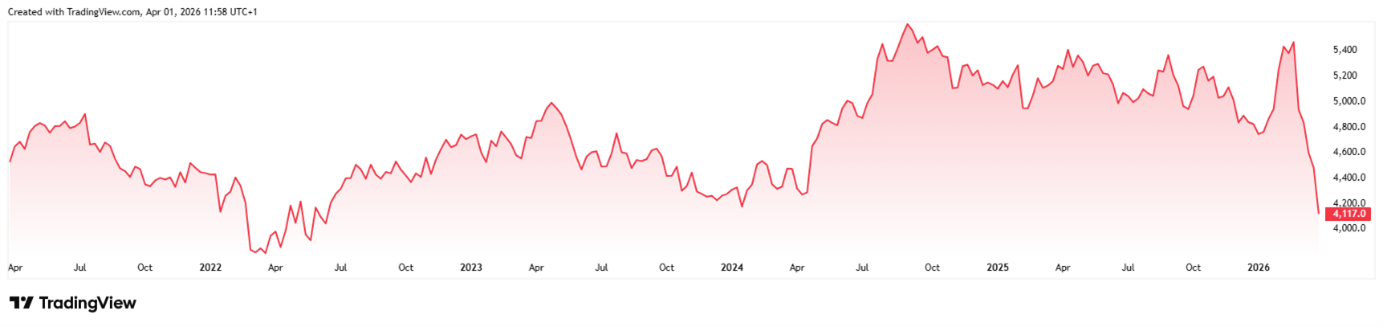
Unilever’s share price performance over the past five years*
What the market will be watching next
The coming months will not be about the $65 billion figure in the headline, but about whether the companies can convince the market that the entire deal has a clear execution logic. The key will be how smoothly it passes regulatory scrutiny, whether it can maintain the pace of integration, and whether McCormick can realistically deliver the promised synergies without the entire deal drowning in higher debt and operational complications. For Unilever, it will be equally important to demonstrate that, following the spin-off of its food business, the company will remain strategically cleaner, faster-growing, and more attractive to investors, not just smaller. If successful, today’s controversial deal may in hindsight prove to be one of the most significant moves in the company’s modern history.[4]
InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., with its registered office at Slávičie údolie 106, Bratislava – Staré Mesto district, 811 02. The company is registered in the Commercial Register of the Municipal Court Bratislava III, Section: Sa, File No.: 4295/B, ID No.: 36 853 054, VAT No.: 2022505419.
CAPITAL MARKETS, o.c.p., a.s. is a securities dealer pursuant to Section 55(1) of Act No. 566/2001 Coll. on Securities and Investment Services and on Amendments to Certain Acts, as amended (hereinafter the “Securities Act”). On October 30, 2007, CAPITAL MARKETS, o.c.p., a.s. was granted, by Decision No. OPK-2297/2007 of the National Bank of Slovakia-PLP, a license to provide investment services pursuant to Section 54(2) in conjunction with Sections 59(2) and (3) of the Securities Act, which was extended in accordance with the provisions of the Securities Act by Decision No. OPK-1830/2008-PLP dated April 21, 2008, Decision No. OPK-11601-1/2008 dated January 28, 2009, Decision No. ODT-5059-3/2012 dated July 23, 2012, and Decision No. ODT-9332/2014-1 dated October 21, 2014.
* Past performance is not a guarantee of future returns.
[1]https://ir.mccormick.com/news-releases/news-release-details/mccormick-combine-unilevers-foods-business-creating-preeminent
[2]https://hk.marketscreener.com/news/unilever-in-takeover-talks-with-mccormick-for-food-business-ce7e5edfd881f323
[3]https://www.reuters.com/legal/transactional/unilever-mccormick-investors-find-65-billion-food-deal-hard-swallow-2026-03-31/
[4]https://www.reuters.com/legal/transactional/unilever-says-nears-deal-merge-foods-unit-with-mccormick-2026-03-31/



