
 English

 Slovak
 Czech
 Hungarian
 Italian
 Polish
 Slovenian


In the fourth quarter, Broadcom achieved adjusted earnings per share of USD 1.95, comfortably surpassing analysts’ expectations surveyed by the London Stock Exchange Group. This figure was calculated on revenues that increased by 28% year over year to USD 18.02 billion, once again well above the analyst consensus. As a result, the company confirmed that its growth is not merely a reflection of the success of a single product line, but rather of a broader portfolio expansion toward data centers and artificial intelligence. An integral part of the quarterly figures is, of course, net income, which in this case increased year over year by 97% to USD 8.51 billion, highlighting a significant improvement in operating efficiency and a strong ability to monetize the growing demand for AI solutions.
Business Segmentation
During the earnings release, investors were naturally interested in which business segment contributed the most to the final profit. In Broadcom’s case, it was clearly the Semiconductor Solutions segment, which generated revenues of USD 11.07 billion, representing a 22% increase compared to the previous year. AI-related revenues within this segment alone rose by 74%, confirming that Broadcom’s semiconductor business is successfully shifting from traditional applications toward AI infrastructure.
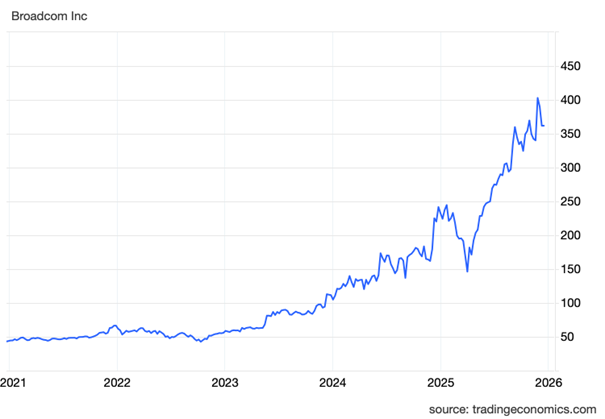
Broadcom share price performance over the last five years*
Notable results were also delivered by the Infrastructure Software segment, including VMware, which reported revenues of USD 6.94 billion and year-over-year growth of 26%. This segment is exceptionally important for the company, as it provides stable, high-margin income that effectively complements the more cyclical semiconductor business.
Outlook for Q1
The outlook for the first quarter of fiscal year 2026 is equally positive. During this period, the company expects to generate revenues of USD 19.1 billion, representing a 28% increase compared to the same period last year. [1] Management also confirmed that the primary driver of this growth will be AI solutions, with AI revenues alone expected to reach USD 8.2 billion in the first quarter.
Long-Term Visibility
Continuing with the company’s fundamental parameters, one of the most important signals for investors is the 18-month order backlog totaling USD 73 billion. This volume includes custom AI chips, network switches, and other key components for data centers. Such a high backlog provides Broadcom with exceptional visibility into future revenues and simultaneously reduces the risk of a sudden slowdown in demand, representing a significant competitive advantage.
Shares and Investor Returns
Market reaction to the results was mixed. Broadcom shares initially rose following the earnings release, but later declined by more than 4%.* This movement should be viewed in a broader context – the company’s value is still approximately 50% higher in 2025, which suggests that this short-term decline may be seen as an opportunity to purchase a fundamentally attractive company at a discounted price. In addition, the company continues to return capital to shareholders – management increased the dividend to USD 0.65 per share, confirming confidence in long-term cash flow as well as the ability to combine growth with regular income.
* Data relating to the past are not a guarantee of future returns.
[1] Forward-looking statements represent assumptions and current expectations that may not be accurate or may be based on the current economic environment, which may change. These statements do not guarantee future performance. Forward-looking statements inherently involve risks and uncertainties, as they relate to future events and circumstances that cannot be predicted, and actual developments and results may differ materially from those expressed or implied in any forward-looking statements.
Disclaimer! This marketing material is not and must not be understood as investment advice. Data relating to the past do not guarantee future returns. Investing in foreign currencies may affect returns due to fluctuations. All securities transactions may lead to both profits and losses. Forward-looking statements represent assumptions and current expectations that may not be accurate or may be based on the current economic environment, which may change. These statements do not guarantee future performance. InvestingFox is a trading brand of CAPITAL MARKETS, o.c.p., a.s., regulated by the National Bank of Slovakia.
Sources:
https://www.cnbc.com/2025/12/11/broadcom-avgo-q4-earnings-2025.html
https://investors.broadcom.com/news-releases/news-release-details/broadcom-inc-announces-fourth-quarter-and-fiscal-year-2025



