Back to blog

Gen Z Darling in Trouble: As Pinterest’s Popularity Hits Records, Investors Count Losses

In the investment world, it is generally true that even a historical maximum in platform popularity may not be enough if unfavorable macroeconomics come into play. Pinterest is currently at exactly this paradoxical point. Although its ecosystem has never been more extensive, Q4 financial results and an uncertain outlook for early 2026 triggered a wave of sell-offs.

Gen Z Darling in Trouble: As Pinterest’s Popularity Hits Records, Investors Count Losses
Results Below Expectations

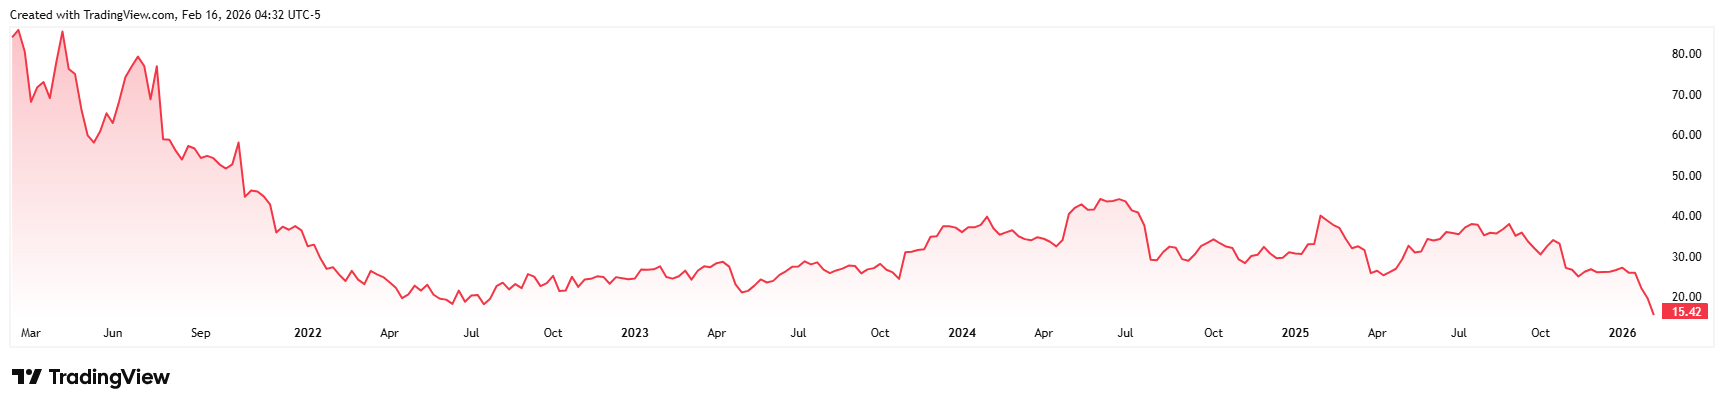
Pinterest closed the past quarter with revenue of $1.32 billion, narrowly missing estimates from analysts surveyed by the London Stock Exchange Group (LSEG) at $1.33 billion. However, the most significant hit was to net profit, which reached $277 million. This represents a significant 85% year-over-year drop, as the company managed a profit of $1.85 billion in the previous year. Lastly, the adjusted EBITDA figure of $541.5 million failed to meet analyst expectations. Combined with a weak Q1 outlook (projecting revenue below the analyst-expected $980 million threshold), this resulted in a nearly 20% drop in stock price on Friday.*
PINS_2026-02-16_10-32-42

Pinterest stock price performance over the last five years*

Impact of Global Tariffs

The main cause of Pinterest's weakened financial performance is not user interest, as many investors likely think, but a specific external factor. CEO Bill Ready has spoken openly about challenges related to tariffs. Pinterest holds a specific position compared to its competitors—its advertising portfolio consists largely of major retailers. These retailers are most affected by new tariffs, which subsequently forced them to immediately and significantly cut digital advertising spend. This high exposure to retail makes Pinterest much more vulnerable to trade decisions than other giants operating in this segment.

Bet on AI

Company management is responding decisively to this unfavorable environment. In January, Pinterest announced a plan to lay off nearly 15% of its employees to increase efficiency. The changes also include a reduction in office space. However, the saved capital isn't just going into savings—according to management, capital expenditures are being directed toward AI. In other words, financial resources are being massively shifted to development teams working on next-generation algorithms for better product targeting and content personalization, aimed at driving profitability in the medium term.

The Power of Gen Z

Despite the financial risks mentioned above, the fundamental side—represented by the user base—remains exceptionally strong. The number of monthly active users grew by 12% year-over-year to a record 619 million. Critically for the future, Gen Z is the fastest-growing demographic group on the platform. This group views Pinterest not only as a place for inspiration but increasingly as a tool for direct shopping, which ultimately confirms the strategic direction toward the platform's e-commerce features.

Investment Perspective

The current situation has split leading investment banks into two camps. Citi downgraded the stock to Neutral, reflecting immediate risks associated with macroeconomic instability. On the other hand, Goldman Sachs acknowledges short-term headwinds but remains optimistic for the long term. For investors, the key question is whether the 20%+ correction is an overreaction to temporary macroeconomic influences or a signal of deeper structural problems. However, if Pinterest successfully integrates AI into its business model and maintains the favor of the younger generation, the current decline may be seen as a risky but potentially advantageous entry point for those who believe in the future of visual search.[1]

[1] Forward-looking statements represent assumptions and current expectations that may not be accurate or are based on the current economic environment, which is subject to change. These statements do not guarantee future performance. Forward-looking statements by their nature involve risk and uncertainty because they relate to future events and circumstances that cannot be predicted, and actual developments and results may differ materially from those expressed or implied in any forward-looking statements.

* Past performance data is no guarantee of future returns.

Sources:

https://investor.pinterestinc.com/financials/quarterly-results/default.aspx https://s204.q4cdn.com/369458543/files/doc_earnings/2025/q4/earnings-result/Q425-PressRelease.pdf

https://s204.q4cdn.com/369458543/files/doc_earnings/2025/q4/presentation/2025-Q4-IR-Earnings-Presentation.pdf

https://www.cnbc.com/2026/02/13/-pinterest-stock-price-tariff-earnings-layoffs.html

InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., with its registered office at Slávičie údolie 106, Bratislava – Staré Mesto district, 811 02. The company is registered in the Commercial Register of the Municipal Court Bratislava III, Section: Sa, File No.: 4295/B, ID No.: 36 853 054, VAT No.: 2022505419.

CAPITAL MARKETS, o.c.p., a.s. is a securities dealer pursuant to Section 55(1) of Act No. 566/2001 Coll. on Securities and Investment Services and on Amendments to Certain Acts, as amended (hereinafter the “Securities Act”). On October 30, 2007, CAPITAL MARKETS, o.c.p., a.s. was granted, by Decision No. OPK-2297/2007 of the National Bank of Slovakia -PLP, a license to provide investment services pursuant to Section 54(2) in conjunction with Sections 59(2) and (3) of the Securities Act, which was extended in accordance with the provisions of the Securities Act by Decision No. OPK-1830/2008-PLP dated April 21, 2008, Decision No. OPK-11601-1/2008 dated January 28, 2009, Decision No. ODT-5059-3/2012 dated July 23, 2012, and Decision No. ODT-9332/2014-1 dated October 21, 2014.

Read more

Oracle Gains Momentum in AI: Cloud Revenue Grows 121%, Contracted Order Volume Reaches $664 Billion

Oracle Gains Momentum in AI: Cloud Revenue Grows 121%, Contracted Order Volume Reaches $664 Billion

Oracle kicked off the new fiscal year with results that once again confirmed that its transformation toward the cloud and artificial intelligence is gaining momentum. The company exceeded market expectations and demonstrated significant acceleration in the areas where it has directed the bulk of its investments in recent years. Behind the strong numbers, however, lies a question that will become increasingly important for investors. Oracle is growing rapidly, but the path to further expansion will be extremely costly. [1]

Casey’s Beat Expectations, but Shares Plummeted: Strong Earnings Overshadowed by a Slowdown in Sales

Casey’s Beat Expectations, but Shares Plummeted: Strong Earnings Overshadowed by a Slowdown in Sales

Casey’s General Stores kicked off fiscal year 2027 with results that, at first glance, appear very impressive. However, behind the strong numbers lies a story that is significantly more complex and raises more questions than clear answers for investors. The market isn’t just looking at how much the company earned, but also at how it achieved this result and whether it will be able to maintain a similar pace in the coming quarters.

The End of Visionary Dreams: In Autonomous Transportation, It’s No Longer the Cars That Matter, but Logistics

The End of Visionary Dreams: In Autonomous Transportation, It’s No Longer the Cars That Matter, but Logistics

Waymo has entered a phase where it’s no longer just about whether an autonomous car can safely navigate a city. What matters most is how many vehicles the company can deploy, how quickly it can enter new markets, and whether it can keep costs under control in the process. This is precisely where a technological demonstration differs from the real transportation business.

DICK’S Sporting Goods Lost 31% in a Single Day: Foot Locker Goes from a Big Bet to a Big Problem

DICK’S Sporting Goods Lost 31% in a Single Day: Foot Locker Goes from a Big Bet to a Big Problem

DICK’S Sporting Goods released results that, at first glance, appear very impressive. However, behind the significant growth lies a story that is considerably more complex and far less reassuring for investors. Some figures suggest that the company’s major strategic bet is not yet unfolding as expected. The market reacted extremely sharply to this news, and DICK’S Sporting Goods shares plummeted 30.7% to $124.31 following the results, marking the worst trading day in the company’s history.*