Results Beat Wall Street Expectations
Oracle’s total revenue reached $19.3 billion, up 30% year-over-year, while analysts, according to LSEG data, had expected approximately $19.14 billion. Adjusted earnings per share reached $1.92, compared to expectations of $1.74. Strong growth was also evident at the operating level, with GAAP operating income rising 57% to $6.7 billion and net income available to common shareholders increasing 60% to $4.7 billion.
At the same time, however, the results show how rapidly Oracle’s structure itself is changing. The cloud business generated $11.6 billion in revenue, accounting for approximately 60% of the company’s total revenue. In contrast, software revenue fell by 3% to $5.5 billion, a decline Oracle attributes to the ongoing shift of customers from traditional on-premises solutions to the cloud. Hardware revenue rose 15% to $774 million, and services added 5% to $1.4 billion. The company is thus increasingly moving away from the image of a traditional software vendor, with growth driven primarily by cloud infrastructure.1
Cloud infrastructure is becoming the main driver of growth
The most striking figure of the quarter was the growth of the Oracle Cloud Infrastructure segment. Its revenue jumped 121% year-over-year to $7.4 billion. Cloud applications grew significantly more slowly, by 10% to $4.2 billion. This difference clearly shows where Oracle’s main source of expansion lies today. The company is benefiting from the sharp rise in demand for the computing capacity needed to train and run artificial intelligence models.1
During the quarter, Oracle also added another 850 megawatts of data center capacity. Since the end of the previous quarter, it has provided its AI cloud customers with more than 300,000 graphics processing units and nearly tripled the amount of capacity delivered compared to the fourth quarter of fiscal year 2026. This is particularly important because, according to the company, demand for the AI cloud continues to grow faster than the available supply. Oracle is therefore not currently dealing with a shortage of customers, but rather with how quickly it can build enough infrastructure to serve them.1
The $664 billion in contracted orders adds another dimension to growth
Oracle’s remaining contractual obligations garnered even more attention than its revenue itself. RPO reached a record $664 billion, representing a year-over-year increase of $209 billion. In the first quarter alone, the company signed new contracts for AI cloud services worth more than $30 billion. The value of RPO is important to investors because it represents services that have already been contracted but will only gradually be converted into reported revenue.1
Oracle expects that approximately half of the current backlog will be converted into revenue over the next 36 months. The figure of $664 billion also significantly exceeded analysts’ estimates of approximately $639.9 billion. The structure of the new contracts is also important. A large portion involves customers making advance payments or hardware financed by the customers themselves, so Oracle claims that the new orders do not require a further increase in planned capital. This could be crucial, as the company needs to convert the growing volume of contracted orders into revenue without placing an equal amount of pressure on its balance sheet. [2]
AI expansion comes at a high cost
However, strong cloud growth comes with exceptionally high investments. Oracle’s capital expenditures reached approximately $28.5 billion in the first quarter. The company generated operating cash flow of $23 billion, representing a year-over-year increase of 184%; however, after accounting for investments, free cash flow remained approximately $5.4 billion in the red. Nevertheless, the result was better than Wall Street had expected, as analysts had anticipated a negative free cash flow of approximately $9.6 billion.12
Customers themselves are shouldering part of the financial burden. Of the capital expenditures for the first quarter, approximately $11.36 billion was covered by advance payments from clients. Oracle also continues to project annual capital expenditures of between $90 billion and $95 billion and completed a $20 billion stock offering during the quarter. The company plans to raise a total of approximately $40 billion through debt and equity during the current fiscal year. The method of financing further expansion remains one of the key issues investors are watching at Oracle.1
The market wants to see not only growth but also cash returns
Management currently believes that the strong momentum will continue. For the second quarter, it expects total revenue growth in U.S. dollars of between 30% and 34% and cloud revenue growth of between 65% and 71%. Adjusted earnings per share are expected to reach between $1.85 and $1.93. For the full fiscal year 2027, Oracle expects revenue of at least $90 billion and has raised its adjusted earnings per share outlook from $8.05 to $8.10.1 [3]
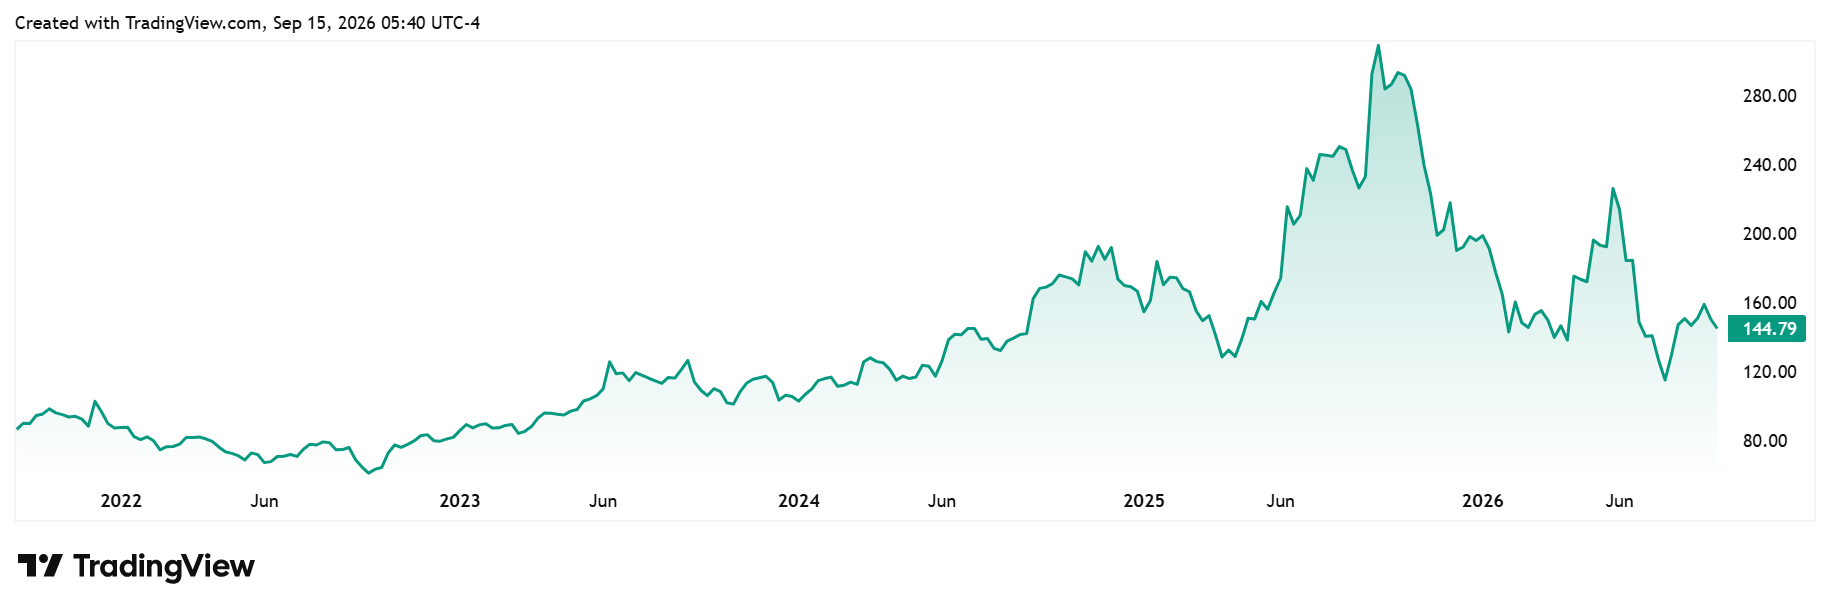
Oracle’s stock price performance over the past five years*
However, the stock market’s reaction showed that growth alone is no longer enough for investors. Oracle’s stock initially rose by about 4% in after-hours trading following the earnings report and climbed as much as 7.8% higher during the next trading session. Later, however, they erased those gains and closed the day down about 2%.* The market thus recognized the record volume of contracted orders, cloud growth, and improved cash flow, but remained cautious due to high capital expenditures, rising financing costs, and uncertainty surrounding the long-term profitability of data centers. The coming quarters will therefore show whether Oracle can convert its $664 billion in contracted orders into revenue quickly enough for the growing cloud business to gradually begin financing its own expansion. This will ultimately determine whether today’s AI boom will translate into higher long-term value for shareholders.13 [4]
[1,2,3,4] Forward-looking statements are based on assumptions and current expectations, which may be inaccurate, or on the current economic environment, which is subject to change. Such statements are not guarantees of future performance. They involve risks and other uncertainties that are difficult to predict. Actual results may differ materially from those expressed or implied in any forward-looking statements.
* Past performance is no guarantee of future returns.
[1] https://investor.oracle.com/investor-news/news-details/2026/Oracle-Announces-Q1-Results-Driven-by-Triple-Digit-Growth-in-Cloud-Infrastructure-Revenues/default.aspx
[2] https://www.reuters.com/technology/oracles-quarterly-revenue-beats-estimates-ai-boom-drives-cloud-demand-2026-09-10/
[3] https://www.reuters.com/business/retail-consumer/oracle-shares-rise-ai-cloud-backlog-beats-estimates-2026-09-11/
InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., with its registered office at Slávičie údolie 106, Bratislava – Staré Mesto district, 811 02. The company is registered in the Commercial Register of the Municipal Court Bratislava III, Section: Sa, File No.: 4295/B, ID No.: 36 853 054, VAT No.: 2022505419.
CAPITAL MARKETS, o.c.p., a.s. is a securities dealer pursuant to Section 55(1) of Act No. 566/2001 Coll. on Securities and Investment Services and on Amendments to Certain Acts, as amended (hereinafter the “Securities Act”). On October 30, 2007, CAPITAL MARKETS, o.c.p., a.s. was granted, by Decision No. OPK-2297/2007 of the National Bank of Slovakia -PLP, a license to provide investment services pursuant to Section 54(2) in conjunction with Sections 59(2) and (3) of the Securities Act, which was extended in accordance with the provisions of the Securities Act by Decision No. OPK-1830/2008-PLP dated April 21, 2008, Decision No. OPK-11601-1/2008 dated January 28, 2009, Decision No. ODT-5059-3/2012 dated July 23, 2012, and Decision No. ODT-9332/2014-1 dated October 21, 2014.

 English

 Slovak
 Czech
 Hungarian
 Italian
 Polish
 Slovenian