Back to blog

SK Hynix Hits New High as It Builds South Korea’s Largest Data Center

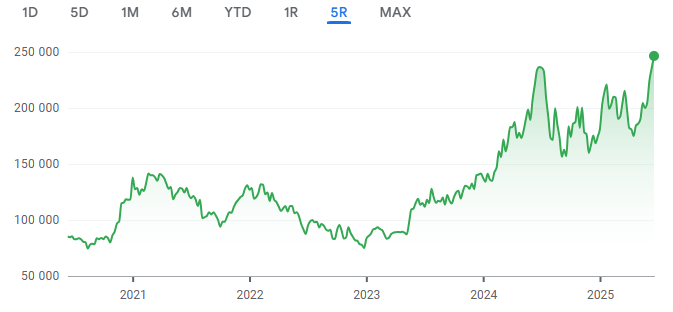
For SK Hynix, a manufacturer of state-of-the-art semiconductors from Korea, 2025 has so far been as successful as the previous one. This proves that last year's 30% rise in share price was not accidental and the company is doing everything it can to maintain the momentum.* The latest is the plan to build the largest data center in cooperation with Amazon, which has the potential to strengthen the 50% increase in the value of shares since April, even further.

SK Hynix Hits New High as It Builds South Korea’s Largest Data Center

Výstřižek

SK Hynix share price performance over the past five years (Source: Google Finance)

Dominant areas

The Korean giant has long profiled itself as the leading manufacturer of key memories with the DRAM label, where it managed to leapfrog Samsung in terms of sales for the first time in the first quarter of 2025, thus appropriating a DRAM market share of 36%. Of course, the company does not forget about the diversification of the product portfolio, and thus the sources of income, and it is undoubtedly worth mentioning the 70% share of the HBM memory market.

With such a majority stake, SK Hynix is not only a leader, but also a key supplier for technology giants such as Nvidia, which ultimately, thanks to advances in artificial intelligence in recent years, represents a long-term stable demand for SK Hynix solutions. Of course, the company is aware of its strength, which is why the aforementioned construction of the largest data center in South Korea was announced.

Cooperation with Amazon

SK Group, the parent company of SK Hynix, chose Amazon for this project, specifically its cloud division Amazon Web Services, known as AWS. In addition, the construction is strategically planned in the city of Ulsan, because such a large-scale project will require a significant supply of electricity, which will be covered by the SK Gas power plant.

Competition and market position

When evaluating individual stock titles, it is also important to evaluate the closest competition, which in this case is Samsung. Above in the text, we mentioned surpassing Samsung in terms of DRAM revenue, but the story is far from over. Samsung's market capitalization has recently fallen to a 9-year low, so the difference in the dynamics of the share price of these two semiconductor industry players is clear. SK Hynix is reaching new absolute highs, while Samsung has been losing for a long time.

What does Wall Street say?

Given all these factors, analysts at leading investment banks based on Wall Street, such as Morgan Stanley, are raising their estimates of future profits for SK Hynix, which would undoubtedly help the rising share price even more. Following this, the company is expected to continue to maintain its strong position, with the greatest growth potential still lying in its ability to respond to the expanding AI market. [1]

Conclusion

In recent years, SK Hynix has been a prime example of a technology leader that not only adapts to current trends, but above all determines their future direction, especially in the field of semiconductors and artificial intelligence. Ultimately, this represents an opportunity for investors to tap into the potential of a company with a solid foundation, at the forefront of technical innovation.

* Historical figures are not a guarantee of future returns.

[1] Forward-looking statements represent assumptions and current expectations that may not be accurate or are based on the current economic environment, which is subject to change. These statements do not guarantee future performance. Forward-looking statements involve risk and uncertainty by their nature because they relate to future events and circumstances that cannot be foreseen, and actual developments and results may differ materially from those expressed or implied in any forward-looking statements.   

Warning! This marketing material is not and should not be construed as investment advice. Data relating to the past are not a guarantee of future returns. Investing in foreign currency can affect returns due to fluctuations. All securities trades can lead to both profits and losses. Forward-looking statements represent assumptions and current expectations that may not be accurate or are based on the current economic environment, which is subject to change. These statements do not guarantee future performance. InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., regulated by the National Bank of Slovakia

Resources:

https://www.cnbc.com/2025/06/17/sk-hynix-shares-extend-gains-on-ai-data-center-plans.html

https://www.koreatimes.co.kr/economy/20250616/samsung-electronics-market-cap-falls-to-9-year-low

https://www.kedglobal.com/tech,-media-telecom/newsView/ked202506160002

https://en.yna.co.kr/view/AEN20250616004500320?section=k-biz/corporate

https://www.counterpointresearch.com/insight/post-insight-research-notes-blogs-sk-hynix-takes-top-spot-for-first-time-on-continued-hbm-demand

InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., with its registered office at Slávičie údolie 106, Bratislava – Staré Mesto district, 811 02. The company is registered in the Commercial Register of the Municipal Court Bratislava III, Section: Sa, File No.: 4295/B, ID No.: 36 853 054, VAT No.: 2022505419.

CAPITAL MARKETS, o.c.p., a.s. is a securities dealer pursuant to Section 55(1) of Act No. 566/2001 Coll. on Securities and Investment Services and on Amendments to Certain Acts, as amended (hereinafter the “Securities Act”). On October 30, 2007, CAPITAL MARKETS, o.c.p., a.s. was granted, by Decision No. OPK-2297/2007 of the National Bank of Slovakia -PLP, a license to provide investment services pursuant to Section 54(2) in conjunction with Sections 59(2) and (3) of the Securities Act, which was extended in accordance with the provisions of the Securities Act by Decision No. OPK-1830/2008-PLP dated April 21, 2008, Decision No. OPK-11601-1/2008 dated January 28, 2009, Decision No. ODT-5059-3/2012 dated July 23, 2012, and Decision No. ODT-9332/2014-1 dated October 21, 2014.

Read more

AutoZone Surprises Wall Street with Earnings: EPS Jumps 15%, but Weaker Sales Reveal Pressure on Customers

AutoZone Surprises Wall Street with Earnings: EPS Jumps 15%, but Weaker Sales Reveal Pressure on Customers

AutoZone closed fiscal year 2026 with results that appear very strong at first glance. Fourth-quarter revenue rose 5.6% year-over-year to $6.59 billion, net income increased to $931.6 million, and earnings per share reached $56.05, approximately 15% higher than a year ago and above Wall Street expectations. Beneath the surface, however, a weakness remains. Comparable sales growth fell short of forecasts, and American DIY car repairers continue to curb their purchases.1

Oracle Gains Momentum in AI: Cloud Revenue Grows 121%, Contracted Order Volume Reaches $664 Billion

Oracle Gains Momentum in AI: Cloud Revenue Grows 121%, Contracted Order Volume Reaches $664 Billion

Oracle kicked off the new fiscal year with results that once again confirmed that its transformation toward the cloud and artificial intelligence is gaining momentum. The company exceeded market expectations and demonstrated significant acceleration in the areas where it has directed the bulk of its investments in recent years. Behind the strong numbers, however, lies a question that will become increasingly important for investors. Oracle is growing rapidly, but the path to further expansion will be extremely costly. [1]

Casey’s Beat Expectations, but Shares Plummeted: Strong Earnings Overshadowed by a Slowdown in Sales

Casey’s Beat Expectations, but Shares Plummeted: Strong Earnings Overshadowed by a Slowdown in Sales

Casey’s General Stores kicked off fiscal year 2027 with results that, at first glance, appear very impressive. However, behind the strong numbers lies a story that is significantly more complex and raises more questions than clear answers for investors. The market isn’t just looking at how much the company earned, but also at how it achieved this result and whether it will be able to maintain a similar pace in the coming quarters.

The End of Visionary Dreams: In Autonomous Transportation, It’s No Longer the Cars That Matter, but Logistics

The End of Visionary Dreams: In Autonomous Transportation, It’s No Longer the Cars That Matter, but Logistics

Waymo has entered a phase where it’s no longer just about whether an autonomous car can safely navigate a city. What matters most is how many vehicles the company can deploy, how quickly it can enter new markets, and whether it can keep costs under control in the process. This is precisely where a technological demonstration differs from the real transportation business.