Japanese Interest Rates Highest in 17 Years, Yen Strengthens
January 27, 2025
After the Bank of Japan (BoJ) ended an eight-year period of negative interest rates last year, it implemented its third rate hike this month. The Japanese yen (JPY) strengthened against other major currencies, driven largely by the rhetoric of the new U.S. president regarding the Federal Reserve's monetary policy and tariffs.
BoJ Rate Hike in Line with Expectations
The BoJ raised its short-term interest rates by another 25 basis points to 0.5%, marking the highest level since 2008. This decision was made in response to rising inflation and slowing economic growth. Recent macroeconomic indicators confirmed this trend, with annual inflation rate rising to 3.6%, the highest since January 2023. GDP growth forecasts for 2024, according to Investing.com, were revised down to 0.4% to 0.6%, with expected figures for this year ranging from 0.9% to 1.1%.
Japan will hold House of Councillors election in July. Therefore, further rate cuts are expected once the political situation stabilizes. However, according to BoJ Governor Kazuo Ueda, what will be important will be data and further inflation developments. Yet, Japan's economy is heavily influenced by developments in the United States, particularly the actions of the new administration under Donald Trump.
Yen Strengthens Against Dollar and Other Currencies
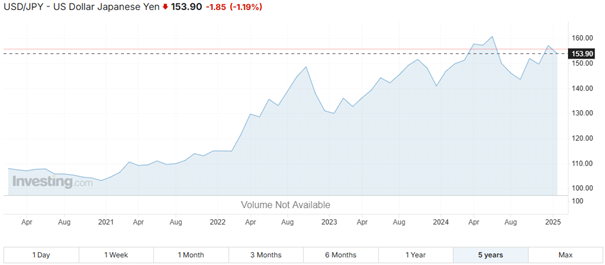
Trump's rhetoric has caused the U.S. dollar to weaken, benefiting the yen. At the World Economic Forum in Davos, the U.S. president urged the Federal Reserve to cut interest rates immediately. Over the past month, JPY has seen a slight strengthening against major global currencies. After the BoJ's rate hike on January 24, 2025, the USD/JPY pair was trading around 156. The BoJ's decision exerted pressure on the U.S. dollar, as the interest rate differential between the U.S. and Japan narrows.* The yen is also benefiting from increased capital flows into safe-haven assets, as it is traditionally seen as a safe haven in times of global uncertainty.
Source: investing.com*
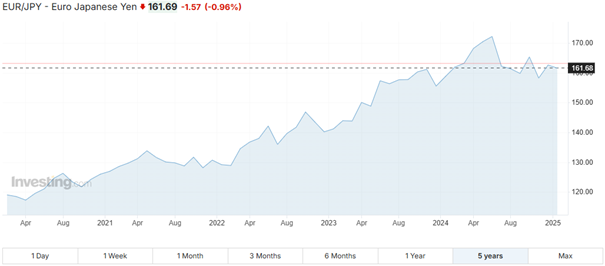
The euro has also weakened against the yen, reflecting the divergence between the European Central Bank's (ECB) and BoJ's monetary policies.* While the ECB continues to keep rates high, it is expected to lower them this month as inflation in the eurozone slows. Weaker economic data from Germany, the largest economy in the eurozone, is contributing to the euro's weakening, providing additional support for the yen. Meanwhile, the BoJ has signalled that its policy tightening will continue.
Source: investing.com*
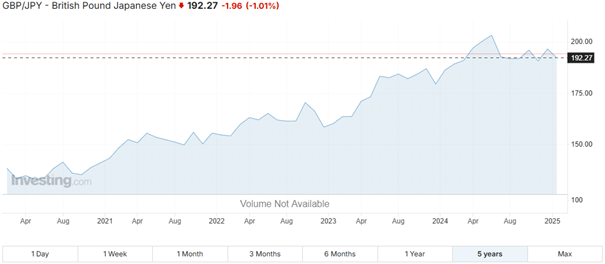
The yen's strength against the British pound (GBP) can be attributed to political and economic factors in the United Kingdom.* The government is under pressure due to concerns over rising deficits and high living costs. Additionally, the Bank of England (BoE) has indicated that its rate hike cycle is nearing its end, reducing the pound's appeal against the yen, which still has potential for further growth.
Source: investing.com*
Other Asian currencies have also strengthened, with hopes for improved global trade conditions and the possibility that announced tariffs may not be implemented immediately.
BoJ Remains Cautious
Kazuo Ueda emphasized caution regarding future steps in monetary policy. The downward revision of the potential growth estimate is primarily due to labor shortages, which may have only a minimal impact on the "neutral" interest rate range. The bank sees them as between 1% and 2.5%. The BoJ has indicated that once interest rates approach the neutral level, it will respond to any adverse economic effects, especially a decline in real estate investment. However, the biggest risks are associated with the potential implementation of U.S. tariffs, which could also harm Japan's economy.
* Historical data is not a guarantee of future returns.
Warning! This marketing material is not and should not be construed as investment advice. Historical data is not a guarantee of future returns. Investing in foreign currencies may affect returns due to fluctuations. All securities transactions may result in both profits and losses. Forward-looking statements represent assumptions and current expectations that may not be accurate or are based on the current economic environment, which may change. These statements do not guarantee future performance. InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s. regulated by the National Bank of Slovakia.
Sources:
https://tradingeconomics.com/japan/interest-rate
https://tradingeconomics.com/japan/inflation-cpi
https://www.investing.com/news/economy/boj-hikes-interest-rates-by-25-bps-sees-slower-growth-and-higher-inflation-3828732
https://www.investing.com/news/economy-news/boj-likely-to-raise-rates-to-highest-in-17-years-signal-more-hikes-3827767
https://apnews.com/article/japan-boj-rates-inflation-interest-economy-e5bb4087ad431850bdb8700c85040e1d
https://www.investing.com/news/forex-news/asia-fx-rebounds-on-trumps-rate-cut-calls-yen-rises-on-boj-rate-hike-3828738
https://www.reuters.com/markets/asia/boj-governor-uedas-comments-news-conference-2025-01-24/
InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., with its registered office at Slávičie údolie 106, Bratislava – Staré Mesto district, 811 02. The company is registered in the Commercial Register of the Municipal Court Bratislava III, Section: Sa, File No.: 4295/B, ID No.: 36 853 054, VAT No.: 2022505419.
CAPITAL MARKETS, o.c.p., a.s. is a securities dealer pursuant to Section 55(1) of Act No. 566/2001 Coll. on Securities and Investment Services and on Amendments to Certain Acts, as amended (hereinafter the “Securities Act”). On October 30, 2007, CAPITAL MARKETS, o.c.p., a.s. was granted, by Decision No. OPK-2297/2007 of the National Bank of Slovakia -PLP, a license to provide investment services pursuant to Section 54(2) in conjunction with Sections 59(2) and (3) of the Securities Act, which was extended in accordance with the provisions of the Securities Act by Decision No. OPK-1830/2008-PLP dated April 21, 2008, Decision No. OPK-11601-1/2008 dated January 28, 2009, Decision No. ODT-5059-3/2012 dated July 23, 2012, and Decision No. ODT-9332/2014-1 dated October 21, 2014.

 English

 Slovak
 Czech
 Hungarian
 Italian
 Polish
 Slovenian