Hungarian

 English
 Slovak
 Czech
 Italian
 Polish
 Slovenian


The results showed a significant turnaround in performance
For the third quarter of 2026, the company reported revenue of $14.58 billion, compared to $5.58 billion a year ago. Year-over-year growth reached 161%. Net income totaled $4.40 billion, while in the same period last year, the company posted a net loss of $1.05 billion.
Operating income reached $2.79 billion, compared to a loss of $273 million last year. Net income was also supported by non-operating items, including other income of $1.03 billion and a positive tax effect of $390 million. When evaluating the results, it is therefore important to distinguish between operating performance and other accounting effects.1
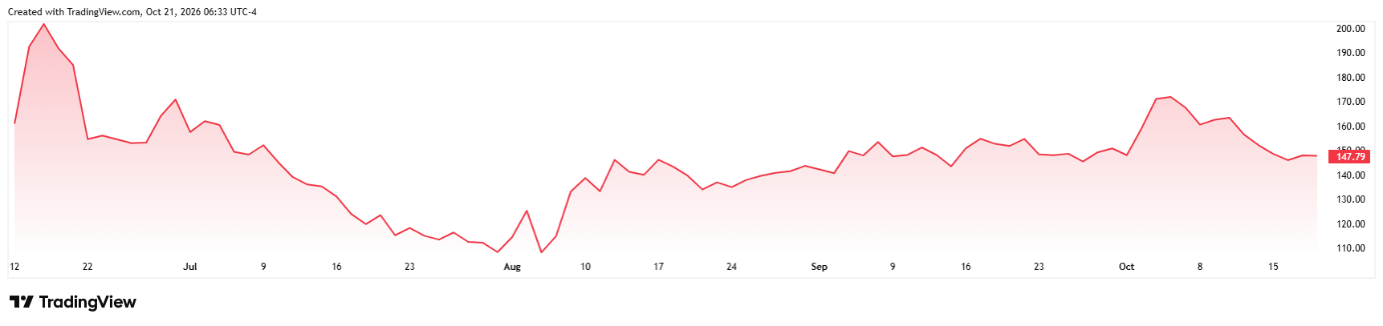
SpaceX’s stock price performance since its IPO.*
Artificial intelligence takes on a pivotal role
Super Intelligence, which encompasses AI, computing infrastructure, and the advertising business, became the largest division by revenue. Its revenue grew by 830% to $7.56 billion and accounted for approximately 52% of the group’s total revenue. However, the division’s operating profit reached $431 million, significantly less than in the satellite business.1
CFO Bret Johnsen attributed the sharp growth primarily to the launch of new cloud service contracts. Of the approximately $7 billion in revenue from AI solutions and infrastructure, the acquired company Cursor contributed $608 million. Even without this contribution, revenue from this segment grew by 192% quarter-over-quarter. A significant portion of the growth is therefore related to the sale of computing capacity to customers.
Starlink is profitable, but expansion requires billions
Starlink reached 13.6 million consumer subscribers, up from 7.2 million a year ago. The Connectivity division increased revenue by 69% to $5.25 billion and generated an operating profit of $2.37 billion. It thus remains the group’s main source of operating profit. However, average monthly revenue per consumer subscriber fell year-over-year from $83 to $69.1
At the same time, rapid expansion comes at a high cost. SpaceX’s capital expenditures in the third quarter reached $19.6 billion, exceeding total revenue. The CFO expects another $35 to $40 billion for the fourth quarter. It is therefore important for investors to monitor how sales growth translates into cash available to finance further investments. Net income alone is not sufficient to assess the financial demands of the expansion. [2]
What was actually agreed upon with Tesla
During the earnings call, Musk confirmed that SpaceX and Tesla had formed special committees composed of independent board members at the request of shareholders. He himself is not participating in their deliberations due to a conflict of interest. The committees have not yet agreed on the terms of the transaction, and according to Musk, there is no guarantee that they will reach an agreement. Therefore, a potential merger cannot yet be considered a done deal.3
The strategic rationale behind the potential merger lies in the integration of AI, energy, robotics, and communications. As Reuters explains, Tesla’s batteries and energy storage systems could power SpaceX’s data centers, while Starlink could provide connectivity to autonomous systems. The companies are already collaborating on the Terafab chip project. However, it would be important for shareholders to see a concrete quantification of the benefits of the joint venture. [3]
What the market will be watching next
SpaceX management expects revenue of $33 to $37 billion in the first quarter of 2027. At the same time, it noted that the gross margin in the fourth quarter should be closer to the second-quarter level, as the third quarter was also supported by a one-time favorable mix of customers. The market will thus evaluate not only the pace of growth but also the level of profitability the company can maintain as it continues to expand capacity.2 [4]
In the event of a potential merger, the key factors will be the valuation of both companies, the ownership structure, and a convincing justification of the benefits for both groups of shareholders. Regulatory issues could also pose a significant obstacle. SpaceX works for U.S. defense and space agencies, while Tesla has a major manufacturing base in China. As Reuters points out, their merger could trigger thorough scrutiny in both the U.S. and China.4 [5]
* Past performance is no guarantee of future returns.
[1,2,3,4,5] Forward-looking statements represent assumptions and current expectations that may not be accurate or are based on the current economic environment, which is subject to change. These statements do not guarantee future performance. By their nature, forward-looking statements involve risk and uncertainty because they relate to future events and circumstances that cannot be predicted, and actual developments and results may differ materially from those expressed or implied in any forward-looking statements.
Warning! This marketing material is not and should not be construed as investment advice. Past performance is no guarantee of future returns. Investing in foreign currencies may affect returns due to fluctuations. All securities transactions may result in either gains or losses. Forward-looking statements represent assumptions and current expectations that may not be accurate or are based on the current economic environment, which is subject to change. These statements do not guarantee future performance. InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., regulated by the National Bank of Slovakia.
[1]https://www.sec.gov/Archives/edgar/data/1181412/000162828026066482/spaceexplorationtechnologi.htm
[2] https://stockanalysis.com/stocks/spcx/transcripts/723936-q3-2026/
[4] https://www.reuters.com/legal/transactional/why-would-musk-merge-spacex-tesla-2026-10-21/