Back to blog

Fintech Under Pressure: JPMorgan Introduces Paid Access to Client Data

In the heart of Manhattan, a relatively subtle yet crucial moment recently took place, which could redefine the future of the American financial sector. JPMorgan Chase, the largest American bank by assets and deposits, announced the conclusion of historic agreements with all the major fintech intermediaries behind most of the third-party data requests in the country. Fintech Under Pressure: JPMorgan Introduces Paid Access to Client Data
American Open Banking

The conflict between banks and fintech startups over who should pay for access to client data has been ongoing for several years. However, the situation has now reached a point where we are witnessing the first compromise. JPMorgan will now start charging fees for API access to data, fundamentally changing the nature of open banking in the United States. "The contracts will make the open banking ecosystem safer and more sustainable, enabling clients to continue using their favorite financial products reliably and securely, and the market has functioned," said the bank’s spokesperson, Drew Pusateri.
jpm_us

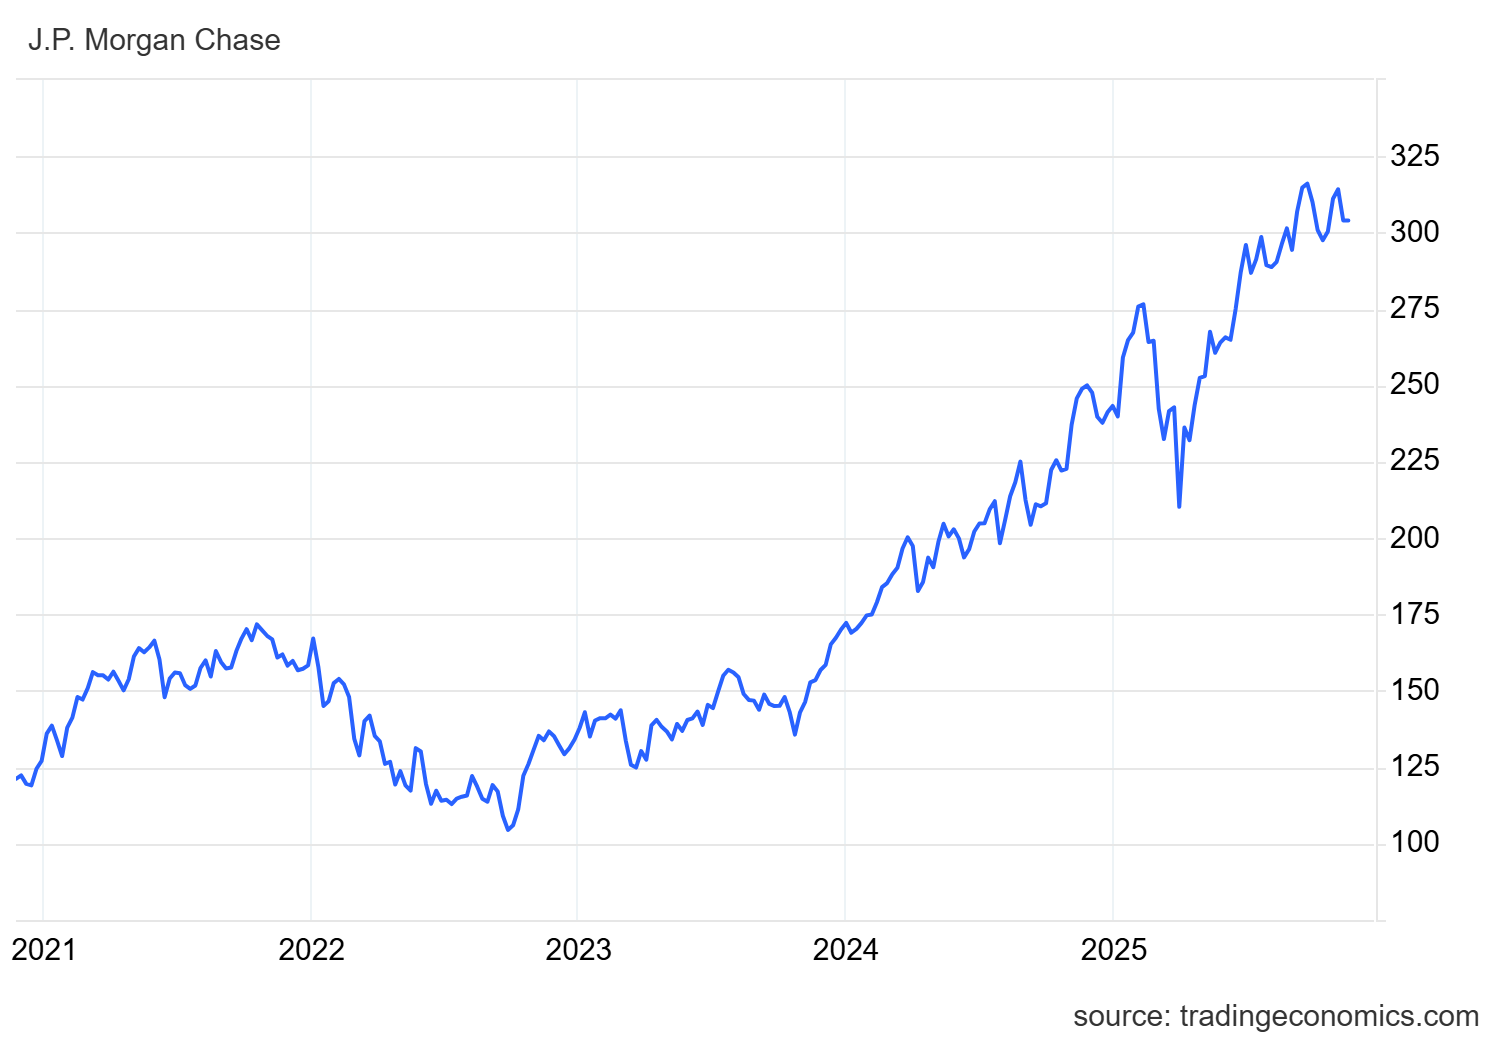
Performance of JPMorgan Chase’s Stock Price Over the Last Five Years*

On the other hand, the situation should be viewed in a more complex manner – for the first time, banks are gaining real control over the data flows driving the fintech ecosystem.

From Regulation to Monetization

As mentioned above, JPMorgan did not arrive at this agreement by chance. Within the genesis of court proceedings, it is crucial to highlight the turning point in 2024 when the Consumer Financial Protection Bureau (CFPB) adopted the so-called open banking rule, mandating banks to share data for free. However, after the arrival of Donald Trump’s administration, the situation drastically changed. In May 2025, the government requested a federal court to immediately revoke the rule. This step paved the way for a new market model where data is directly transformed into a commercial commodity. Following this, JPMorgan immediately announced its intention to charge fintech companies hundreds of millions of USD.

Long-Term Potential

Naturally, JPMorgan achieved its desired strategic solution. The bank gains a new, and most importantly, stable source of income outside traditional lending and investment banking – this time from data infrastructure. Access fees from large fintech firms could generate hundreds of millions of USD annually, while also allowing the bank to fund the development and maintenance of its API systems.

More importantly, JPMorgan is securing its position as a gateway to financial data, through which all leading fintech applications must pass. Last but not least, the bank has been performing well on the stock market; since the beginning of the new decade, it has seen stable stock price development, with the company’s value increase this year already over 25%.*

*Past data is not a guarantee of future returns.

Disclaimer! This marketing material is not and should not be construed as investment advice. Past data is not a guarantee of future returns. Investing in foreign currency may affect returns due to fluctuations. All securities transactions may lead to both gains and losses. Forward-looking statements represent assumptions and current expectations, which may not be accurate or may be based on the current economic environment, which may change. These statements do not guarantee future performance. InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., regulated by the National Bank of Slovakia.

Sources:

https://www.cnbc.com/2025/11/14/jpmorgan-chase-fintech-fees.html

https://www.cnbc.com/2025/07/28/jpmorgan-fintech-middlemen-plaid-data-requests-taxing-systems.html

https://www.cnbc.com/2025/07/31/jpmorgan-1000th-branch-opening-expansion-plans.html

InvestingFox is a trademark of CAPITAL MARKETS, o.c.p., a.s., with its registered office at Slávičie údolie 106, Bratislava – Staré Mesto district, 811 02. The company is registered in the Commercial Register of the Municipal Court Bratislava III, Section: Sa, File No.: 4295/B, ID No.: 36 853 054, VAT No.: 2022505419.

CAPITAL MARKETS, o.c.p., a.s. is a securities dealer pursuant to Section 55(1) of Act No. 566/2001 Coll. on Securities and Investment Services and on Amendments to Certain Acts, as amended (hereinafter the “Securities Act”). On October 30, 2007, CAPITAL MARKETS, o.c.p., a.s. was granted, by Decision No. OPK-2297/2007 of the National Bank of Slovakia -PLP, a license to provide investment services pursuant to Section 54(2) in conjunction with Sections 59(2) and (3) of the Securities Act, which was extended in accordance with the provisions of the Securities Act by Decision No. OPK-1830/2008-PLP dated April 21, 2008, Decision No. OPK-11601-1/2008 dated January 28, 2009, Decision No. ODT-5059-3/2012 dated July 23, 2012, and Decision No. ODT-9332/2014-1 dated October 21, 2014.

Read more

TD SYNNEX Far Exceeded Expectations: Revenue Jumped 38%, but Shares Fell After the Earnings Report

TD SYNNEX Far Exceeded Expectations: Revenue Jumped 38%, but Shares Fell After the Earnings Report

TD SYNNEX reported results that, at first glance, look very strong and confirm that the company is benefiting from growing demand for technology infrastructure. Upon closer inspection, however, the picture is not entirely clear-cut. Behind the record numbers lies a combination of rapid expansion, shifting margins, and significant cash flow fluctuations, which investors have begun to view with far greater sensitivity than revenue growth alone. It is precisely the difference between what the income statement shows and what is happening beneath the surface that makes TD SYNNEX’s latest quarter a much more interesting story than the headline numbers alone would suggest.

AutoZone Surprises Wall Street with Earnings: EPS Jumps 15%, but Weaker Sales Reveal Pressure on Customers

AutoZone Surprises Wall Street with Earnings: EPS Jumps 15%, but Weaker Sales Reveal Pressure on Customers

AutoZone closed fiscal year 2026 with results that appear very strong at first glance. Fourth-quarter revenue rose 5.6% year-over-year to $6.59 billion, net income increased to $931.6 million, and earnings per share reached $56.05, approximately 15% higher than a year ago and above Wall Street expectations. Beneath the surface, however, a weakness remains. Comparable sales growth fell short of forecasts, and American DIY car repairers continue to curb their purchases.1

Oracle Gains Momentum in AI: Cloud Revenue Grows 121%, Contracted Order Volume Reaches $664 Billion

Oracle Gains Momentum in AI: Cloud Revenue Grows 121%, Contracted Order Volume Reaches $664 Billion

Oracle kicked off the new fiscal year with results that once again confirmed that its transformation toward the cloud and artificial intelligence is gaining momentum. The company exceeded market expectations and demonstrated significant acceleration in the areas where it has directed the bulk of its investments in recent years. Behind the strong numbers, however, lies a question that will become increasingly important for investors. Oracle is growing rapidly, but the path to further expansion will be extremely costly. [1]

Casey’s Beat Expectations, but Shares Plummeted: Strong Earnings Overshadowed by a Slowdown in Sales

Casey’s Beat Expectations, but Shares Plummeted: Strong Earnings Overshadowed by a Slowdown in Sales

Casey’s General Stores kicked off fiscal year 2027 with results that, at first glance, appear very impressive. However, behind the strong numbers lies a story that is significantly more complex and raises more questions than clear answers for investors. The market isn’t just looking at how much the company earned, but also at how it achieved this result and whether it will be able to maintain a similar pace in the coming quarters.