English

 Slovak
 Czech
 Hungarian
 Italian
 Polish
 Slovenian


A Historic Quarter Exceeding $20 Billion
Caterpillar’s revenue and other income reached a record $20.543 billion in the second quarter of 2026. Compared to $16.569 billion a year ago, this represents a 24% increase. For the first time in its more than century-long history, the company surpassed the $20 billion mark in a single quarter. The largest portion of the increase came from higher sales volume, which boosted revenue by $3.113 billion. Higher selling prices contributed an additional $595 million, and favorable currency movements added approximately $199 million. Importantly, sales grew across all three major industrial segments, reducing the company’s reliance on any single specific sector.[1]
Moreover, the growth did not stem solely from dealers restocking their inventories. Caterpillar stated that the primary driver of the higher volume was equipment sales to end customers. This is a significant distinction for investors, as growth driven by real demand has a more solid foundation than the temporary movement of equipment into the distribution network. North America was particularly strong, with consolidated revenue rising 37% to $12.094 billion. Europe, Africa, and the Middle East recorded growth of 14%, Latin America 10%, and Asia-Pacific 4%. The results thus demonstrated broad geographic growth, although the main driver continues to come from the U.S. market.1
Profit grew significantly faster than revenue
Operating income rose 50% year-over-year, from $2.860 billion to $4.295 billion. Net income attributable to shareholders increased from $2.179 billion to $3.593 billion. Basic earnings per share reached $7.77, compared to $4.62 a year ago. After adjusting for restructuring costs, adjusted earnings per share were $8.17, while in the same period last year they were $4.72. Caterpillar thus managed to translate 24% revenue growth into significantly faster earnings growth, which points to strong operating leverage and better utilization of production capacity.1
Adjusted earnings per share significantly exceeded the analyst consensus of approximately $6.20. The operating margin rose from 17.3% to 20.9%, and the adjusted operating margin increased from 17.6% to 21.9%. However, the results were also bolstered by an expected tariff refund of $392 million, which added approximately $0.65 to earnings per share. Even after accounting for this item, the strength of the quarter remains evident. Profitability was driven primarily by higher sales volume and more favorable prices, which more than offset the rise in manufacturing, administrative, and R&D costs.1
Construction was the biggest surprise
The Construction Industries segment reported revenue of $8.346 billion, representing year-over-year growth of 35%. Sales volume contributed an additional $1.755 billion, and higher prices added another $309 million. North America was particularly strong, with segment revenue rising 50% to $5.065 billion. Growth was driven by investments in major construction projects, transportation and energy infrastructure, heavy construction, and data centers. The segment’s profit rose by 57% to $1.947 billion, and its margin improved from 20.1% to 23.3%. The Construction division thus delivered the largest absolute increase in both revenue and operating profit.1
However, strong growth was not limited to construction equipment. Revenue for the Power & Energy segment rose by 17% to 8.238 billion USD, and its profit increased by 30% to 2.027 billion USD. Electric power generation alone recorded a 29% increase in revenue to $3.098 billion. Demand was driven by large reciprocating engines, turbines, and maintenance services used primarily in data centers. The Resource Industries segment increased revenue by 20% to $4.648 billion and profit by 23% to $693 million. Caterpillar is thus benefiting simultaneously from data center construction, rising electricity consumption, raw material extraction, and the renewal of railway equipment.1
Orders Point to Continued Growth
The strongest indicator of future performance is the value of the order backlog. At the end of the second quarter, it reached a record $72.1 billion. In just three months, it increased by $9.4 billion and rose by $34.6 billion year-over-year. Caterpillar is thus entering the second half of the year with an order backlog that exceeds its total revenue for the entire year of 2025. The high volume of outstanding orders provides the company with better visibility into future revenue and confirms that demand is expanding across all major segments. This is an important signal for investors, as a weakening in orders is often the first warning sign of a decline in revenue for cyclical industrial companies.1 [1]
Management has therefore raised its outlook and expects full-year 2026 revenue growth to be in the mid-to-high single-digit range. As recently as in the first quarter, the company had anticipated growth only in the low-to-mid range. The adjusted operating margin is expected to be near the lower end of the long-term target range, excluding tariff compensation. Caterpillar also lowered its estimate of full-year costs associated with new tariffs to approximately $2.2 billion. The previous outlook projected a range of $2.2 billion to $2.6 billion. Higher revenue is thus accompanied by a slightly more favorable outlook on the cost environment.1 [2]
Strong cash flow rewards shareholders, but risks remain
Free cash flow from the industrial segment reached $5.1 billion in the second quarter, which was $2.8 billion more than a year ago. Caterpillar returned a total of $2.2 billion to shareholders. $1.5 billion was allocated to share buybacks, and approximately $700 million was used for dividends. The company ended the quarter with $6.7 billion in cash and an additional $1.5 billion in liquid securities. In the first six months of the year, it repurchased more than $6.5 billion of its own shares. This strong cash generation thus enables the company to finance the expansion of production capacity while continuing to provide substantial returns to shareholders.1 [3]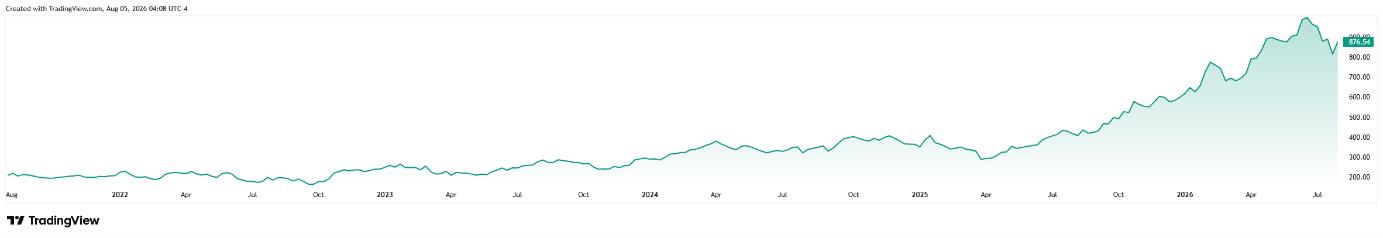
Caterpillar’s stock price performance over the past five years*
The market reacted positively to the results, and Caterpillar shares closed the day up 5.6%, having gained as much as 12% during the trading session. Investors appreciated not only the earnings beat itself, but also the record orders and the upward revision to the outlook. The key question for the coming quarters will be whether the current pace can be sustained. The manufacturing company must expand capacity, manage higher costs, and maintain margins at the same time. Risks include tariffs totaling approximately $2.2 billion, rising production costs, and a potential slowdown in data center construction. However, current results show that Caterpillar is no longer merely an indicator of the traditional construction and mining cycle. It is also becoming a major supplier of the infrastructure needed for the growing digital economy.1[2] [4]
[1,2,3,4] Forward-looking statements are based on assumptions and current expectations, which may be inaccurate, or on the current economic environment, which is subject to change. Such statements are not guarantees of future performance. They involve risks and other uncertainties that are difficult to predict. Actual results may differ materially from those expressed or implied in any forward-looking statements.
* Past performance is no guarantee of future returns.
[1] https://s25.q4cdn.com/358376879/files/doc_financials/2026/q2/2Q-2026-Analyst-Slide-Deck_Final.pdf
[2] https://www.reuters.com/business/caterpillar-second-quarter-profit-jumps-strong-power-construction-equipment-2026-08-04/